
Blogs
PW Consulting: Aluminum Exhibits Market Hits $4,210M in 2025, Projected to Reach $7,088.63M by 2032 at 7.73% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Aluminum Exhibits Market: Navigating Growth and Complexity in 2026
The global aluminum exhibits market stands at a pivotal inflection point. As organizations across trade shows, events, and retail environments demand more modular, sustainable, and technologically integrated display solutions, the strategic importance of precise market intelligence has never been higher. This article serves as a preview of our latest comprehensive market research report, designed to equip executives, investors, and supply chain leaders with the contextual depth needed to make informed decisions throughout 2026 and beyond.
The underlying market dynamics reflect both robust expansion and intensifying structural complexity. Historical performance from 2020 to 2025 demonstrates a trajectory shaped by post-pandemic event recovery, accelerated adoption of lightweight aluminum frameworks, and the rapid digitalization of physical exhibition spaces. Looking forward, our forecast period spanning 2026 through 2032 maps a continued growth pathway underpinned by predictable demand drivers, though one that is simultaneously tested by raw material volatility, shifting trade regulations, and evolving competitive positioning. Understanding where the market is headed, and why, requires moving beyond headline numbers into the operational and strategic layers that actually drive commercial outcomes.
Macro Trajectory and the 2026 Decision Window
The market has expanded materially over the past half-decade, scaling from approximately 1,650 million USD in 2020 to an estimated 4,210 million USD by 2025. That progression reflects more than a simple rebound; it signals a structural recalibration in how exhibitors, event producers, and brand managers approach physical environments. Aluminum's inherent advantages, recyclability, modularity, strength-to-weight ratio, and compatibility with integrated lighting and digital media, have cemented its role as a foundational material in modern exhibit design.
Our forecast model projects the market to reach 4,426.72 million USD in 2026, with growth compounding at a 7.73 percent CAGR through the end of the forecast window. By 2032, the market is positioned to approach the 7,088.63 million USD threshold. These are not abstract projections. They represent a demand environment in which procurement teams must plan for capacity, pricing, and supply continuity; in which manufacturers must decide where to allocate R&D and production resources; and in which investors must distinguish between cyclical noise and durable secular growth.
The 2026 decision window is particularly consequential because multiple forces are converging simultaneously. Demand for reconfigurable and reusable exhibit packages continues to rise as organizations seek to reduce waste, lower total cost of ownership, and maintain brand consistency across multiple event locations. At the same time, the cost and availability of aluminum as a primary input have become critical variables in margin management and pricing strategy. Leaders who treat 2026 as a planning anchor rather than a reactive operating year will be better positioned to capture share while managing downside risk.
Structural Shifts Across Product Types and Applications
The market's growth is not uniform across all product types or end-use applications. Instead, it is being reshaped by clear preference patterns that favor flexibility, speed of deployment, and design precision. Modular systems, which enable rapid assembly, reconfiguration, and reuse across different event footprints, have captured a substantial share of commercial activity. Their appeal lies in their ability to reduce labor costs, shorten setup timelines, and support sustainability objectives by extending the usable life of exhibit assets.
Truss systems continue to serve a distinct but meaningful role, particularly where structural spans, overhead installations, and architectural visibility are priorities. Custom extrusions, meanwhile, cater to organizations that require highly tailored geometries, integrated functional elements, or specialized finishes that standard configurations cannot deliver. Together, these categories illustrate a market that is simultaneously standardizing at the modular level while still rewarding engineering-driven customization where brand differentiation or functional requirements demand it.
Application-side dynamics reinforce this divergence. Trade shows and exhibitions remain the dominant commercial engine, reflecting the ongoing centrality of in-person industry gatherings, product launches, and brand immersion experiences. Events and concerts contribute a notable secondary demand stream, particularly where temporary stage architectures, scenic structures, and branded environments rely on aluminum's portability and load-bearing capabilities. Retail and interior displays represent a growing adjacency, as brands extend exhibit-grade modular logic into permanent or semi-permanent storefront environments, pop-up retail, and experiential showrooms.
What matters for strategic planning is not simply which category is largest, but how these segments interact. Modular platforms increasingly serve as the backbone for multi-application deployments. A single engineered frame may support a trade show booth in one quarter, a concert staging element in another, and a retail display installation thereafter. This cross-application flexibility changes the economics of product development and procurement, placing a premium on systems that can adapt without sacrificing structural integrity or aesthetic consistency.
Aluminum Exhibits Market
Competitive Landscape and the Battle for Differentiation
The competitive environment reflects a blend of established manufacturers, specialized engineering firms, and extrusion specialists, many of which are pursuing differentiation through design capability, material innovation, and technology integration. Several companies have defined themselves through a clear strategic identity rather than competing solely on price.
Aluvision has positioned itself at the intersection of modular aluminum framing and immersive brand environments, with an emphasis on sustainable design and LED-integrated solutions. Its trajectory illustrates how exhibit manufacturers are increasingly expected to deliver more than structural components; they are being asked to support lighting, media integration, and environmentally responsible production practices within a single system.
Agam brings more than four decades of experience in engineered modular aluminum structures and extrusions, serving exhibit companies and agencies that require reliability, repeatability, and technical depth. Its recent industry analysis emphasizes a market-wide shift toward smarter and more efficient modular builds, signaling that performance optimization and material efficiency are becoming core purchasing criteria rather than secondary considerations.
Skyline Exhibits continues to operate across the full spectrum of custom modular trade show exhibits and displays, combining design, manufacturing, and management services with fast-ship kits and full-service deployment options. Its recognition in the 2026 MUSE Creative Awards underscores how creative execution and engineering discipline are increasingly evaluated together by buyers who view exhibits as both functional infrastructure and brand communication tools.
The broader supplier ecosystem includes organizations such as Exhibit and Display Truss, Abex, Extrude-A-Trim, 80/20 Inc., and Nova Display, each contributing distinct capabilities ranging from aluminum truss structures and lightweight reconfigurable booths to T-slot extrusion systems and modular floor stands or showcases. The presence of multiple specialized players indicates a market that rewards technical versatility and responsive service, especially for customers managing tight event schedules or complex installation constraints.
From a concentration standpoint, the market remains moderately fragmented, with the top three players accounting for roughly 32.4 percent of revenue and the top five approaching 45.6 percent. This structure suggests that while scale players hold meaningful influence, there is still substantial room for mid-sized and specialized firms to compete on engineering quality, regional responsiveness, customization depth, and integration capabilities. For procurement leaders, this fragmentation is strategically useful: it supports negotiation leverage, encourages supplier diversification, and allows organizations to match specific vendors to specific project requirements rather than relying on a single universal source.
External Pressures: Materials, Trade Policy, and Supply Dynamics
No strategic assessment of the aluminum exhibits market in 2026 would be complete without confronting the external forces that directly shape cost structures and supply availability. Raw material prices have become a central boardroom topic, and aluminum is no exception. Recent market conditions show aluminum prices moving higher through early 2026, with cash prices climbing above the 3,000 USD per tonne level and extending further as supply concerns and trade policy effects interacted with demand. By mid-May 2026, LME aluminum cash pricing reached approximately 3,564 USD per tonne, a notable year-over-year increase that underscores the importance of monitoring input costs at a granular level.
This pricing environment has direct implications for manufacturers, fabricators, and exhibit buyers. For producers, it reinforces the need for forward sourcing strategies, hedged procurement where appropriate, and design choices that optimize material yield. For exhibit purchasers, it highlights the value of reusable and modular systems that reduce repeated material exposure across multiple events. In practical terms, the organizations that succeed in this environment are those that treat aluminum cost not as a static line item, but as a variable to be managed through product architecture, inventory planning, and supplier relationships.
Trade policy adds another layer of complexity. In April 2026, U.S. Section 232 tariffs on aluminum and derivatives were revised, with rates in the range of 25 to 50 percent on full customs value for many imported aluminum articles, including extrusions that are directly relevant to exhibit manufacturing. Alongside this, an ongoing U.S. antidumping duty administrative review covering aluminum extrusions from China is examining the May 2024 through April 2025 period, with preliminary determinations addressing China-wide entity rates. These developments matter because they affect landed cost, sourcing strategy, and the relative attractiveness of domestic versus imported supply.
The strategic takeaway is not that trade risks are uniformly prohibitive, but that they require deliberate mapping. Companies with exposure to imported extrusions must evaluate tariff impact on product costing, assess alternative sourcing pathways, and consider whether near-term inventory or contract structures can buffer volatility. Companies with domestic production or flexible supply chains may find themselves better positioned to serve customers who prioritize reliability and regulatory predictability. In either case, the firms that incorporate trade dynamics into their planning early will have more options than those that discover exposure only after pricing or availability shifts.
What the Research Report Delivers for Decision-Makers
Our full market research report translates this landscape into an actionable decision framework. It is designed not as a static data reference, but as an operating companion for teams responsible for product strategy, procurement, sales planning, capital allocation, and competitive positioning. The report integrates historical analysis, forward-looking forecasts, segmentation logic, and competitive intelligence into a cohesive narrative that helps leaders answer practical questions about where demand is strengthening, where margins are under pressure, and how to align organizational priorities with market realities.
Worldwide Exhibition Stand Market
Readers can expect a detailed examination of market sizing and growth pathways across the forecast horizon, with explicit attention to the drivers behind the projected expansion and the variables that could accelerate or moderate it. The report addresses the structural role of modular systems, truss systems, and custom extrusions, and it maps how these product categories function across trade shows, events, concerts, retail displays, and related environments. Rather than presenting segmentation as an abstract breakdown, it frames each slice of the market in operational terms: what it demands from suppliers, what buying criteria dominate, and where the most meaningful value creation opportunities lie.
The competitive analysis goes beyond company descriptions to explore strategic positioning, capability differentiation, and the practical implications of recent industry moves. It contextualizes developments such as creative award recognition, the issuance of exhibit trend analyses emphasizing smarter modular builds, and exclusive distribution partnerships for LED-integrated aluminum systems. These events are not treated as isolated news items; they are interpreted as signals of how manufacturers are competing for attention, contracts, and channel advantage in a market where technology integration and design credibility increasingly influence purchasing decisions.
Material and regulatory context is woven throughout, ensuring that strategic recommendations are grounded in the real conditions shaping aluminum availability and cost. The report examines how raw material price movements affect production economics, how revised tariff frameworks alter sourcing trade-offs, and how ongoing trade reviews influence supply-chain confidence. This integrated approach allows decision-makers to connect market growth potential with the practical constraints that determine whether that potential can be captured profitably.
For executives and analysts, the report offers a structured basis for scenario planning. It supports questions such as how to prioritize regional supply flexibility, how to evaluate whether modular reuse programs can offset input cost volatility, how to position product portfolios in a market that rewards both standardization and customization, and how to interpret competitive moves as indicators of where the next wave of differentiation will emerge. In that sense, the research is meant to reduce uncertainty where it matters most: in the choices that shape capacity planning, vendor selection, pricing strategy, and long-term portfolio direction.
Strategic Takeaways for 2026 and Beyond
The aluminum exhibits market is expanding within a landscape that rewards clarity of strategy. Growth is real and measurable, but it is unfolding alongside material cost volatility, trade-policy evolution, and intensifying competition for design-led, technology-enabled exhibit solutions. Organizations that treat these forces as isolated externalities risk underestimating their impact on margins, timelines, and supplier reliability. Those that integrate them into planning will be better equipped to allocate resources, negotiate from a position of insight, and build exhibit systems that remain efficient across multiple deployments.
Several priorities stand out. First, modular and reconfigurable design is no longer a convenience feature; it is increasingly a core economic and sustainability requirement. Second, aluminum pricing and trade regulation should be incorporated into procurement and product strategy early, with explicit attention to sourcing options and landed-cost modeling. Third, competitive differentiation is shifting toward integrated capabilities, including lighting, media compatibility, rapid deployment, and engineering reliability, which means manufacturers and buyers alike must evaluate vendors on total system value rather than component price alone.
Our full report provides the deeper quantitative and qualitative intelligence needed to operationalize these priorities. It delivers the market sizing, growth trajectory, segmentation logic, competitive context, and external risk mapping required to support confident decision-making throughout 2026 and the wider forecast period. For teams seeking a clearer line of sight between market opportunity and execution strategy, the complete analysis offers the level of detail and structural insight that high-stakes planning demands.
For detailed analysis of this topic, please visit the official page: Aluminum Exhibits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Carob Chocolate Bars Market to Reach $350 Million by 2032, Growing at 7.2% CAGR
By pmarketresearch, 2026-09-16
Carob Chocolate Bars Market 2026: Strategic Intelligence for Growth Leadership
Executive Overview
The global carob chocolate bars market is entering a decisive inflection point. As consumer preferences shift decisively toward plant-based, allergen-friendly, and clean-label confectionery alternatives, carob-based bars have moved from niche retail corners to mainstream shelf space. For executive teams, category managers, and innovation directors, the 2026 landscape demands more than surface-level trend tracking. It requires a rigorous, forward-looking intelligence framework that translates macroeconomic trajectories, supply chain realities, and competitive maneuvering into executable strategy. Our latest market research delivers precisely that blueprint. By anchoring historical performance to a structured forecast horizon through 2032, this report equips leadership with the analytical clarity needed to allocate capital, time product pipelines, and outmaneuver competitors in an increasingly crowded health-conscious confectionery segment.
Protein Bars Market
Macro Trajectory: Reading the Growth Signal
The expansion curve for carob chocolate bars reflects steady, compounding momentum rather than speculative hype. Historical tracking from 2020 through 2025 reveals consistent year-over-year appreciation, with the market scaling from approximately 150 million USD to 215 million USD over that five-year window. The forecast period extends this trajectory through 2032, projecting a compound annual growth rate of 7.2 percent. This growth profile is not merely a statistical projection; it is a structural indicator shaped by ingredient substitution dynamics, retail channel evolution, and the broadening consumer acceptance of cocoa alternatives. For strategic planners, the implication is clear: scale opportunities exist, but they will be captured by organizations that align product development cycles, distribution partnerships, and pricing architectures with a market that rewards disciplined execution over speculative positioning.
Report Architecture: What Decision-Makers Will Find Inside
Our methodology is built around operational utility. Rather than delivering high-level summaries that leave implementation gaps, the report is structured to answer the questions that sit on the desks of brand strategists, supply chain directors, and market entry teams. The research framework covers:
- Historical performance tracking across the 2020–2025 baseline, establishing trend confirmation and volatility patterns that inform near-term planning assumptions.
- A forward-looking forecast model spanning the 2026–2032 horizon, with scenario-ready growth pathways designed to support budgeting, capacity planning, and market entry sequencing.
- Segment-level analysis across product formulations and distribution pathways, mapping how different consumer access points and ingredient positioning strategies contribute to overall category expansion.
- Regional market mapping that identifies where demand is consolidating, where retail infrastructure is maturing, and where cross-border supply dynamics are reshaping competitive access.
- Competitive profiling of core manufacturers and innovators, highlighting strategic positioning, product architecture, and recent commercial actions that signal where the market is heading.
- Supply-side and regulatory context, including raw material pricing signals, labeling requirements, and formulation trends that affect margin structures and go-to-market readiness.
Each analytical layer is designed to connect directly to decision processes. The objective is not to describe the market, but to make it actionable.
Carob Chocolate Bars Market
Segmentation Intelligence: Mapping Opportunity Vectors
The category is expanding across multiple product and channel dimensions, and each vector carries distinct implications for brand positioning, margin architecture, and speed-to-market. Product-type dynamics reflect a market where ingredient positioning increasingly dictates purchase behavior. Formulations anchored in organic certification and cleaner ingredient narratives continue to capture disproportionate attention from health-oriented buyers, while conventional offerings maintain relevance through accessibility and price sensitivity. Distribution-channel analysis further illustrates how the category is being absorbed into both legacy retail infrastructure and newer, experience-driven purchasing pathways. Supermarket and hypermarket networks provide the volume foundation for broad consumer reach, specialty health food retailers deliver credibility and targeted audience engagement, and online retail channels enable rapid testing, direct-to-consumer iteration, and geographic expansion without the friction of traditional shelf negotiations. Together, these segments form a multi-speed market in which growth is not uniform, but strategically navigable when mapped correctly.
Competitive Landscape: How the Field Is Shaping Up
The carob chocolate bar category remains relatively fragmented, with market concentration metrics indicating that no single coalition of players dominates overall category economics. This fragmentation is strategically important. It suggests room for differentiation, but it also means that competitive advantage will be earned through product distinctiveness, channel access, and supply chain discipline rather than scale alone. Several companies illustrate the strategic diversity currently shaping the market. Missy J's has built its identity around organic vegan carob treats engineered to be gluten-free, dairy-free, and caffeine-free, drawing on Australian organic carob and positioning clearly within clean-label snacking. The Carob Kitchen operates from a farm-to-bar philosophy in South Australia, offering milk-style, vegan, sugar-free, and no-added-sugar variants that reflect a deep integration between ingredient sourcing and product architecture. Caroboo has pursued a flavor-forward, format-diverse approach in the UK, expanding into variants such as salted caramel, mint, and orange while emphasizing compostable packaging and retail footprint growth. CarobMe has focused on organic bar formulations, including soy-free and gluten-free chocolate substitutes that appeal to allergen-conscious consumers. D&D Chocolates represents a family-run production model in the UK, emphasizing vegan, dairy-free, gluten-free, nut-free, and soya-free alternatives that target sensitive dietary requirements. Carob World, based in Portugal, underscores sustainable sourcing and cocoa-free formulation as central brand pillars. Meanwhile, The Australian Carob Co. plays a supporting role in the value chain by supplying carob products and enabling other brands to expand their carob-based bar portfolios.
Recent commercial and technical developments reinforce the pace of change. In late 2025, Caroboo secured a notable retail listing with Holland & Barrett, strengthening its presence in the UK health retail channel and signaling a deliberate push into premium-positioned distribution. Around the same period, research activity from NUS scientists demonstrated two novel flavor-boosting techniques for carob-based chocolate alternatives, pointing to a broader industry focus on taste parity as a prerequisite for mainstream adoption. In the ingredient space, the launch of a carob-derived prebiotic fiber component illustrated how functional benefits are increasingly being embedded into product narratives relevant to bars and gut-health positioning. These moves matter because they show that competition is no longer limited to taste and packaging. It now extends into flavor engineering, functional formulation, and premium retail access.
Market Dynamics: The Forces Reshaping Margin and Access
Several intersecting dynamics are redefining what it takes to compete profitably. Clean-label expectations and vegan consumption patterns continue to accelerate demand for cocoa alternatives, with formulations frequently delivering meaningfully lower sugar profiles than traditional chocolate. That reduction is not merely a nutritional talking point; it is a purchase driver and a reformulation constraint that influences ingredient selection, cost structure, and consumer perception. At the same time, supply-side conditions are introducing new planning variables. Wholesale carob pod pricing in key sourcing markets has shown notable movement, with export levels in certain segments reaching elevated levels relative to historical norms. Broader trade data also indicates a persistent gap between export and import pricing dynamics, reflecting freight, handling, certification, and channel-markup realities that manufacturers must model into cost planning. These input signals can affect margin flexibility, especially for brands that rely on specific origin sourcing or premium organic certification.
Regulatory and compliance considerations add another layer of strategic relevance. In several markets, imported plant-based food products must meet national labeling standards, including nutritional fact table requirements on packaging. While such rules vary by jurisdiction, the broader implication is consistent: international expansion and multi-market product rollouts require labeling readiness, documentation discipline, and formulation transparency that can withstand regulatory scrutiny. Brands that treat compliance as a backend task rather than a market entry prerequisite risk delays, rework, and shelf-access friction. On the consumer side, the convergence of allergen-sensitive purchasing, plant-based dietary preferences, and sugar-conscious snacking continues to expand the addressable audience for carob bars, but it also raises expectations for clarity, trust, and repeat-purchase quality. The companies that win will be those that align product claims with verifiable formulation logic and maintain consistent quality across channels.
Strategic Value for 2026 Decision-Making
In a market characterized by steady growth but increasing competitive and supply complexity, intelligence is not a luxury; it is an operating requirement. This report is designed to support three core decision priorities. First, it clarifies where growth is most likely to materialize and under what conditions, helping leadership prioritize innovation investments, channel commitments, and regional focus. Second, it contextualizes competitive behavior, enabling brands to anticipate moves in flavor expansion, retail placement, ingredient positioning, and sustainability messaging before those moves reshape shelf dynamics. Third, it integrates supply-side and regulatory considerations into strategic planning, allowing organizations to model cost exposure, prepare for labeling and import requirements, and reduce the risk of reactive decision-making.
The strategic value of this research lies in its orientation toward execution. Rather than stopping at high-level category description, the analysis connects market structure to actionable planning questions: which product narratives align with emerging demand, which distribution environments offer the strongest near-term leverage, where sourcing and input pricing may pressure margins, and how competitive differentiation can be sustained without relying solely on price. For executives evaluating market entry, product extension, channel expansion, or portfolio repositioning, the report provides the structural clarity needed to move from curiosity to commitment.
Navigating the Next Phase with Precision
The carob chocolate bars market is no longer a peripheral alternative category. It is an expanding segment shaped byIngredient-driven consumer choices, retail channel evolution, and a competitive field that is investing in taste, function, and sustainability. The organizations that will benefit most from the forecast period are those that treat growth as something to be engineered through informed positioning, disciplined cost planning, and channel-aware launch strategy. Our full market research unpacks the segment-level detail, regional context, competitive movements, and supply-side signals that leadership needs to act with confidence. The trajectory is clear. The next step is to ensure your strategy is built on the full intelligence behind it.
For detailed analysis of this topic, please visit the official page: Carob Chocolate Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Metal Cutting Gas Market to Hit $7B by 2032, Growing at 5.4% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Decade Ahead: Inside the Worldwide Metal Cutting Gas Market 2026–2032
The global industrial landscape is undergoing a structural recalibration. From supply chain realignment to decarbonization mandates, manufacturing enterprises face a complex web of forces that directly influence production economics. Within this environment, the metal cutting gas market occupies a critical yet often underestimated position. As a foundational input for fabrication, maintenance, and assembly operations, the supply, pricing, and technological evolution of cutting gases increasingly determine operational resilience and cost efficiency across heavy industry. PW Consulting’s newly released Worldwide Metal Cutting Gas Market research provides a comprehensive strategic roadmap for executives navigating this competitive terrain through 2032. This analysis distills the report’s most consequential insights, emphasizing actionable intelligence for 2026 decision-making while preserving the granular data architecture that detailed procurement and investment planning require.
Market Trajectory and Macroeconomic Foundations
Historical performance and forward-looking projections establish a clear narrative of sustained growth tempered by cyclical volatility. Between 2020 and 2025, the worldwide market expanded from approximately 3,750 million USD to 4,850 million USD, reflecting robust industrial recovery, accelerated infrastructure deployment, and steady demand from fabrication-intensive sectors. The forecast window extending through 2032 indicates a compound annual growth rate of 5.4 percent, positioning the market to reach roughly 7,008 million USD by the terminal year. This trajectory signals more than incremental expansion; it reflects a structural shift in how metalworking enterprises source, optimize, and integrate cutting gases into broader operational workflows.
Historical Momentum and Forward Projections
The 2020–2025 period demonstrated remarkable resilience despite macroeconomic disruptions, logistics constraints, and fluctuating feedstock availability. Revenue progression consistently outpaced earlier baselines, underscoring the non-discretionary nature of metal cutting operations in automotive assembly, heavy equipment manufacturing, shipbuilding, and infrastructure development. Looking ahead, the forecast period anticipates acceleration driven by capacity expansions in emerging industrial corridors, modernization of legacy fabrication facilities, and increasing adoption of optimized gas blends that improve cutting efficiency while reducing consumable waste. Analysts tracking the sector note that procurement strategies are evolving from price-centric Purchasing models to integrated supply chain partnerships, where gas delivery reliability, safety compliance, and technical support carry equal weight alongside unit cost.
Structural Drivers Shaping Demand Economics
Several interlocking dynamics will define market behavior throughout the forecast window. First, the ongoing upgrading of metal fabrication capabilities in Asia Pacific and select European corridors continues to elevate baseline consumption. Second, the modernization of legacy cutting equipment toward higher-efficiency oxy-fuel and hybrid plasma configurations creates demand for specialized gas formulations that maximize flame temperature, reduce oxygen consumption, and minimize slag formation. Third, regulatory environments are tightening around hazardous air pollutants, transportation safety for compressed gases, and emissions standards in integrated steel and metal processing facilities. These regulations do not merely constrain operations; they reshape procurement specifications, incentivize cleaner-burning fuel blends, and increase the strategic value of suppliers capable of delivering compliant, technically supported gas solutions.
Metal Cutting Tools Market
Feedstock pricing remains a persistent variable. Recent market observations indicate divergent regional pricing patterns for acetylene, with European benchmarks reflecting upward pressure linked to calcium carbide supply dynamics, while North American pricing has tracked alongside varied downstream fabrication demand. Such divergences reinforce the necessity of region-specific sourcing strategies rather than one-size-fits-all procurement frameworks. Enterprises that map feedstock exposure, logistics constraints, and regional regulatory timelines into their gas purchasing architecture will secure a measurable competitive advantage.
Segmentation Intelligence and Application Realities
Effective strategy requires precise segmentation mapping. The Worldwide Metal Cutting Gas Market research decomposes the ecosystem across three critical axes: geographic distribution, gas type classification, and end-use application segments. Each layer reveals distinct demand drivers, competitive intensity, and growth vectors that general market summaries frequently obscure.
Geographic Dynamics and Regional Demand Patterns
Regional analysis within the report illuminates where industrial activity concentrates, where infrastructure investment accelerates, and where procurement frameworks diverge. The data architecture identifies Asia Pacific as the largest revenue contributor, reflecting massive fabrication output, expanding shipbuilding and offshore repair capacity, and sustained automotive and transportation manufacturing. Europe maintains a substantial share supported by mature industrial ecosystems, stringent safety and emissions standards, and ongoing equipment modernization cycles. North America rounds out the top tier, driven by heavy machinery production, defense-related fabrication, and resilient construction and infrastructure spending. Middle East and Africa, alongside Latin America, represent specialized but strategically important corridors where localized supply networks, import dependencies, and project-based demand create distinct sourcing requirements.
Importantly, the report avoids superficial regional generalizations. Instead, it maps regional demand against local feedstock availability, regulatory calendars, logistics infrastructure, and the presence of key supplier operations. This approach enables executives to evaluate market entry opportunities, assess supply chain vulnerability, and calibrate inventory strategies according to regional risk profiles rather than global averages.
Gas Type Classification and Technical Differentiation
The gas type segmentation captures a market far more diverse than legacy acetylene-centric assumptions suggest. Acetylene remains a dominant share contributor, valued for its high flame temperature and versatility across traditional oxy-fuel cutting applications. Propane follows as a widely deployed alternative, offering cost advantages and safety profile benefits for specific fabrication workflows. Propylene occupies a strategic middle ground, particularly where operators seek enhanced cutting performance with reduced oxygen consumption. Methane and natural gas segments reflect ongoing integration of utility-scale gas infrastructure into industrial fabrication environments, while specialty fuel blends represent a growing niche for precision applications requiring customized combustion characteristics.
Worldwide Metal Cutting Gas Market
Each gas type carries distinct handling requirements, storage considerations, equipment compatibility constraints, and regulatory implications. The report details how these technical differentiators influence procurement decisions, vendor selection, and in-house operational training. Executives evaluating supplier portfolios will find direct relevance in the segmentation analysis, particularly when matching gas chemistry to cutting process specifications and compliance mandates.
Application Segments and End-Market Alignment
Understanding where cutting gases are consumed unlocks clearer forecasts of demand stability, cyclical exposure, and growth acceleration. Automotive and transportation applications represent a leading consumption segment, reflecting high-volume fabrication, body-in-white cutting, chassis component processing, and aftermarket maintenance operations. Heavy machinery and industrial equipment follow closely, encompassing earthmoving equipment, agricultural machinery, and specialized industrial component fabrication that demands robustness and consistent cut quality. Shipbuilding and offshore repair form a structurally significant segment, where project-based demand peaks align with vessel construction cycles, fleet maintenance schedules, and offshore platform rehabilitation programs.
Construction and infrastructure applications provide a steady baseline driven by structural steel processing, pipeline fabrication, and civil engineering projects. Aerospace and defense represent a technically demanding segment where precision, material compatibility, and stringent quality assurance protocols elevate the importance of gas consistency and supplier technical support. The report’s application segmentation enables stakeholders to map demand volatility, identify procurement cycles, and anticipate where equipment upgrades or process optimizations will trigger gas specification changes.
Competitive Architecture and Strategic Positioning
Market concentration data indicates that the three largest competitors collectively command approximately 38.4 percent of global revenue, while the top five firms extend their combined share to roughly 52.6 percent. This concentration profile suggests a market structure where global integrators hold substantial influence, yet meaningful regional and specialized players maintain viable competitive positions through localized distribution networks, application-specific expertise, and strong customer relationships. Understanding this architecture is essential for procurement leaders evaluating supplier diversification, for investors assessing market entry barriers, and for executives planning partnership or acquisition strategies.
Global Integrators and Their Operational Footprints
Linde plc stands as a major global supplier of industrial gases, including oxygen, acetylene, propane, and specialized mixtures tailored for oxy-fuel metal cutting, plasma cutting, and laser cutting applications across metal fabrication workflows. Its worldwide operational presence enables coordinated supply across multiple regions, while technical service capabilities support complex fabrication environments. Air Liquide S.A. operates as a leading producer and distributor of cutting gases such as oxygen, acetylene, and fuel gas blends, complemented by oxy-fuel cutting equipment and integrated solutions for worldwide metal fabrication and manufacturing. The company’s position reflects deep integration between gas supply, equipment provision, and application engineering.
Air Products and Chemicals, Inc. supplies oxy-fuel cutting gases, including propylene-based cutting solutions, alongside laser and plasma cutting gases and total solutions for metal cutting applications globally. Its portfolio emphasizes performance optimization and process integration. Messer SE & Co. KGaA operates as a specialized provider of industrial gases and solutions for metal industry applications, including cutting and welding gases for fabrication, with a strong presence across Europe, the Americas, and Asia. Its regional depth and technical specialization make it a significant competitor in markets where localized service and application knowledge drive purchasing decisions.
Regional Specialists and Fuel Gas Suppliers
Beyond the global integrators, a cohort of regional and fuel-focused suppliers shapes competitive dynamics through specialized product offerings and geographic proximity. TotalEnergies SE supplies fuel gases including propane and specialized cutting gas formulations for oxy-fuel metal cutting processes, leveraging broader energy sector infrastructure and fuel distribution capabilities. Indian Oil Corporation Ltd provides Indane NANOCUT and other LPG-based cutting gases optimized for high flame temperature and low oxygen consumption in metal cutting applications, addressing regional demand with formulations designed for operational efficiency. Bharat Petroleum Corporation Limited supplies industrial and cutting gases, including LPG variants for metal cutting and fabrication in Indian and export markets, supporting both domestic fabrication and cross-border supply requirements.
Brothers Gas operates as a regional supplier of industrial cutting gases and mixtures for oxy-fuel and other metal cutting processes across Middle East and international markets, filling a strategic role in regions where localized availability and rapid response logistics influence procurement decisions. NISSAN TANAKA CORPORATION functions as a manufacturer and supplier of gases and equipment focused on metal cutting and welding applications in Japan, combining gas supply with equipment integration for technically advanced fabrication environments. ESAB, part of the Colfax group, provides cutting gases alongside welding and cutting equipment and consumables for metal fabrication worldwide, positioning itself at the intersection of consumable supply and equipment solutions.
Competitive Differentiation and Procurement Implications
The competitive landscape rewards suppliers that deliver more than volume. Technical consultation, safety compliance support, delivery reliability, formulation customization, and equipment-gas compatibility expertise increasingly differentiate market participants. Procurement teams evaluating supplier partnerships should consider how each competitor’s operational footprint aligns with regional demand, how their product portfolio maps to cutting process requirements, and how their service infrastructure mitigates supply disruption risk. The report’s competitive analysis provides a structured framework for these evaluations, enabling data-driven supplier selection rather than relationship-led assumptions.
Operational, Regulatory, and Supply Chain Context
Market behavior does not occur in isolation. Regulatory frameworks, raw material dynamics, and transportation safety requirements continuously reshape operational parameters. Recent developments highlight the practical relevance of these forces. In the United States, the Environmental Protection Agency maintains national emission standards for hazardous air pollutants applicable to integrated iron and steel manufacturing facilities, covering sinter plants, blast furnaces, and basic oxygen process shops that influence related metal processing gas usage. These standards encourage fabricators and their gas suppliers to align specifications with emissions compliance, often favoring formulations and process configurations that reduce atmospheric impact.
Simultaneously, the U.S. Department of Transportation’s Pipeline and Hazardous Materials Safety Administration oversees hazardous materials transportation regulations for compressed gases including acetylene and oxygen used in metal cutting, with ongoing research into pipeline safety and leak detection standards. Transportation compliance affects delivery scheduling, packaging choices, storage design, and risk management protocols, making regulatory tracking an operational necessity rather than a peripheral concern.
On the trade policy front, Section 232 tariffs on steel and aluminum imports underwent restructuring in April 2026, shifting application to the full customs value of certain finished products containing metals. This adjustment can influence metal fabrication costs and, indirectly, gas demand by altering the cost structure of imported components and domestic substitution incentives. Enterprises with exposure to tariff-affected supply chains should reassess procurement sourcing, inventory positioning, and gas consumption forecasts as part of broader cost and supply chain planning.
Raw material pricing adds another layer of complexity. Acetylene pricing in Europe has reflected upward movement linked to calcium carbide feedstock costs, while North American acetylene pricing has tracked alongside downstream fabrication demand with periodic increases. These dynamics underscore the importance of feedstock monitoring, contract structuring, and alternative gas type evaluation when cost volatility emerges. Suppliers and buyers alike benefit from anticipating feedstock-driven pricing shifts rather than reacting after margins compress.
What the Report Delivers for 2026 Decision-Makers
PW Consulting’s Worldwide Metal Cutting Gas Market research translates macro trends, segmentation detail, competitive intelligence, and regulatory context into a decision-ready intelligence package. The report is designed for executives who require more than headline figures. It structures information to support strategic planning, procurement optimization, supplier evaluation, market entry assessment, and risk mitigation.
Scope, Methodology, and Analytical Depth
The analysis covers historical performance from 2020 through 2025 and projects market behavior across the 2026–2032 forecast window, all expressed in million USD with a clearly documented compound annual growth rate. This temporal span enables readers to understand how past disruptions, recovery patterns, and investment cycles inform future expectations. Methodological rigor ensures that projections are grounded in observable demand drivers, segmentation logic, and competitive behavior rather than generic extrapolation.
Actionable frameworks for procurement and strategy teams
Beyond forecasts, the report provides practical frameworks that procurement and strategy teams can apply immediately. These include segmentation mapping that clarifies where demand concentrates and how it evolves, competitive profiling that distinguishes global integrators from regional specialists and fuel-focused suppliers, and regulatory tracking that highlights compliance inflection points affecting gas selection, transportation, and storage. The research also incorporates application-level insights that help align gas specifications with cutting process requirements, equipment configurations, and quality assurance standards.
For executives evaluating capital allocation, the report supports scenario planning by outlining where growth is most probable, which segments face cyclical exposure, and how regulatory or feedstock shocks could alter cost structures. For supplier relationship managers, it provides a structured lens to assess vendor capability beyond price, focusing on reliability, technical support, compliance alignment, and regional coverage. For investors and market entrants, it delineates concentration dynamics, differentiation opportunities, and the practical barriers that shape competitive viability.
Connecting data to execution
A distinguishing feature of the research is its emphasis on execution relevance. Market size and growth rates matter, but their strategic value emerges when tied to actionable choices: which gas types align with specific cutting applications, which regions present the strongest demand trajectory relative to supply risk, which competitors offer complementary capabilities, and which regulatory timelines require proactive preparation. The report is organized to facilitate these connections, enabling readers to move from awareness to action without reconstructing the analytical logic themselves.
Conclusion: Making Informed Moves in a Shifting Market
The worldwide metal cutting gas market is not a static commodity environment. It is a technically nuanced, regionally diverse, and competitively layered ecosystem in which procurement decisions, supplier partnerships, regulatory preparedness, and feedstock awareness converge to shape operational performance. The 2026–2032 forecast window presents both opportunity and complexity. Growth is sustained, but its distribution across regions, gas types, and applications requires careful evaluation. Competition is concentrated at the top yet remains dynamic through regional specialists and fuel-focused suppliers. Regulatory and trade developments introduce variables that reward proactive planning.
PW Consulting’s comprehensive market research equips executives with the intelligence necessary to navigate this environment with confidence. By combining rigorous market sizing, detailed segmentation, competitive profiling, and operational context, the report delivers a strategic foundation for 2026 decision-making and beyond. To access the full dataset, regional breakdowns, application-level analysis, and complete competitive assessments, we invite stakeholders to visit the source page and obtain the complete Worldwide Metal Cutting Gas Market research. Detailed intelligence remains the most reliable basis for strategic action, and the complete report provides exactly that.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Cutting Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Global Piriformis Syndrome Market to Reach $320.96M by 2032 at 5.51% CAGR
By pmarketresearch, 2026-09-16
Navigating the Piriformis Syndrome Market: Strategic Imperatives for 2026 and Beyond
The piriformis syndrome market is entering a pivotal phase of maturation, shaped by advancing minimally invasive techniques, evolving reimbursement frameworks, and a growing emphasis on multimodal pain management. As healthcare systems worldwide continue to refine treatment pathways for this complex neuromuscular condition, stakeholders require granular, forward-looking intelligence to allocate capital, position product portfolios, and anticipate competitive shifts. This analysis introduces our latest Worldwide Piriformis Syndrome Market research, a comprehensive intelligence asset designed to equip executives, investors, and clinical strategists with the decision-grade insights needed to navigate the 2026 to 2032 horizon with confidence.
Market Trajectory and Strategic Context
Over the past half-decade, the global market for piriformis syndrome interventions has demonstrated steady, structurally supported expansion. Drawing on historical performance through the base year of 2025, our research traces a consistent upward trajectory that reflects both rising diagnostic awareness and the broader shift toward targeted, outcome-driven musculoskeletal care. Looking ahead, the market is projected to reach a substantial valuation by 2032, underpinned by a compound annual growth rate that signals durable, mid-single-digit expansion across the forecast window. This growth is not accidental; it is being engineered by converging clinical, regulatory, and technological forces that are reshaping how providers approach piriformis-related pain, nerve compression, and functional impairment.
For enterprise leaders, the strategic implications are clear. The expanding market envelope creates room for differentiated value propositions, but it also raises the bar for clinical evidence, reimbursement alignment, and patient-accessibility. Companies that treat this landscape as a static commodity opportunity will likely encounter margin pressure and share erosion. Conversely, organizations that embed clinical validation, delivery-model innovation, and payer-ready documentation into their go-to-market architectures will be positioned to capture premium positioning as treatment algorithms continue to evolve.
What This Research Delivers: A Blueprint for Decision-Making
Our Worldwide Piriformis Syndrome Market study is structured as an actionable intelligence platform rather than a high-level snapshot. It integrates historical baselines, forward-looking projections, and deep qualitative context across the full treatment continuum. The report provides a rigorous examination of how conservative management, minimally invasive procedures, and surgical interventions are competing for clinical adoption, reimbursement favor, and patient preference. It further dissects the distribution ecosystem, mapping how hospitals, specialized clinics, and retail pharmacy channels are shaping access, pricing dynamics, and service integration.
Worldwide Piriformis Syndrome Market
Beyond macro-volume projections, the research delivers operational granularity that executives can translate directly into planning. Key deliverables include:
- A detailed segmentation architecture that clarifies how treatment modalities are performing across clinical settings, patient segments, and delivery pathways
- Competitive benchmarking that evaluates product positioning, procedural differentiation, and commercial strategy across leading participants
- Regulatory and reimbursement intelligence that contextualizes coding guidance, coverage determinations, and the compliance considerations influencing procedure adoption
- Clinical and practice-pattern analysis that synthesizes the role of pharmacotherapy, injectables, neuromodulation devices, and therapy-based protocols within multidisciplinary care models
- Market concentration metrics that illuminate the competitive weight of dominant players and the structural room for entrants and niche innovators
The report is built to support scenario planning. Whether the question is how to prioritize R&D investment, where to expand clinical partnerships, or how to anticipate payer behavior in the next coverage cycle, the analysis is calibrated to translate epidemiological and procedural signals into executable strategy.
Competitive Landscape: Differentiation in a Fragmented Field
The piriformis syndrome market remains comparatively fragmented, with a diverse mix of device innovators, pharmaceutical suppliers, therapy-equipment manufacturers, and specialized procedural providers competing across overlapping value chains. Concentration is moderate rather than consolidated, creating both opportunity and complexity. Incumbents must defend share across multiple modalities, while new entrants can target underserved clinical niches or delivery gaps if they bring credible evidence and clear reimbursement pathways.
Among procedural specialists, Deuk Spine Institute has advanced a distinctive outpatient surgical approach with its patented Piriformis Release technique, emphasizing a minimally invasive, permanent intervention delivered through a small incision. The company’s recent promotion of this procedure highlights a broader industry movement toward outpatient, low-downtime solutions that align with cost-conscious care delivery and patient demand for faster recovery profiles. This shift reflects an important strategic theme: procedural durability and safety narratives are becoming critical commercial assets in a space where clinicians and payers increasingly weigh long-term outcomes against upfront intervention risk.
In the pharmaceutical and injectable segment, multiple global players contribute to conservative and interventional treatment protocols. Allergan, under AbbVie, provides onabotulinumtoxinA as an adjunct to physical therapy, positioning botulinum toxin within a broader spasm-relief and nerve-compression management framework. Bayer and Novartis support the conservative pharmacotherapy backbone through NSAIDs and muscle relaxants, while Sanofi and Teva diversify access through branded and generic pain-management options. Endo Pharmaceuticals adds further depth to the pain-management supply chain, reinforcing the centrality of pharmacological intervention in initial and adjunctive care pathways.
The non-invasive and device-adjacent segment is equally active. King Brand Healthcare Products markets specialized cold and heat therapy wraps tailored to piriformis symptom relief and muscle recovery, while Omron Healthcare supplies TENS technology relevant to non-pharmacological symptom management. Recent device-oriented activity, including the promotion of wearable TENS solutions by Hinge Health, underscores a growing appetite for home-accessible, low-risk modalities that can complement clinical care and extend the patient experience beyond the point of service.
From a strategic standpoint, the competitive picture suggests that future share gains will not come from any single product category alone. The winners are likely to be those who integrate across modalities, align with clinical workflows, and demonstrate value across the patient journey. Companies that operate in silos may find their addressable market constrained by treatment algorithms that increasingly favor combined, stepped-care approaches.
Clinical Evidence, Regulation, and Reimbursement as Strategic Variables
Market growth in this space is inseparable from the evolving evidence and policy environment. Clinical research continues to refine procedural selection and comparative effectiveness. Recent trial activity, including randomized comparisons of ultrasound-guided corticosteroid injection against extracorporeal shockwave therapy, signals an intensifying focus on objective efficacy data and modality optimization. Ongoing trial listings examining post-facilitation stretch, active release techniques, and shockwave-based interventions further indicate that the field is moving toward more rigorous, protocol-level differentiation rather than reliance on anecdotal adoption.
On the regulatory and reimbursement side, policy clarity is both an enabler and a constraint. CMS billing and coding guidance for piriformis muscle injections continues to shape procedural documentation standards, while also emphasizing that certain imaging-guided needle placement methods may not consistently demonstrate additional clinical benefit over landmark-based approaches. This creates a practical compliance consideration for providers and device or injector suppliers: procedural claims and documentation strategies must align with payer expectations around necessity, efficiency, and evidence of marginal value.
Reimbursement determinations are equally influential for injectables. Medicare Local Coverage Determinations have recognized botulinum toxins as reasonable and necessary for certain off-label applications under defined criteria, including refractory piriformis syndrome when appropriate conditions are met. For pharmaceutical participants, this kind of coverage architecture can materially affect adoption ceilings, prescribing behavior, and commercial forecasting. It also reinforces the importance of building payer-facing evidence packages that address not just clinical mechanism, but real-world appropriateness and patient selection logic.
At the same time, the broader treatment philosophy is shifting toward integrated conservative care. Physical therapy approaches encompassing myofascial release, hip abductor strengthening, and neuromuscular inhibition techniques are increasingly viewed as foundational elements, often combined with pharmacotherapy or targeted injections. Surgical intervention, including laparoscopic decompression or piriformis resection, remains generally reserved for severe refractory cases after conservative and interventional options have been exhausted. This stepwise, escalation-based model matters strategically because it influences where volume accumulates, which modalities gain earlier-line adoption, and which companies benefit from downstream procedural demand.
The regulatory environment for injectables is also relevant. Multiple FDA-approved botulinum toxin type A products carry established use in muscle-related conditions applicable to piriformis syndrome management. This approval landscape does not automatically translate into uniform market performance, but it does create a structured backdrop in which clinical differentiation, administration workflows, and reimbursement compatibility become decisive competitive factors.
Strategic Takeaways for 2026 Decision-Makers
As organizations plan their 2026 moves, several themes should dominate the strategic agenda:
Worldwide Tendinitis Treatment Market
- Evidence-led positioning will increasingly separate durable franchises from transient demand. Clinical studies, real-world outcomes, and payer-acceptable documentation are becoming central to adoption velocity.
- Convergence across conservative, interventional, and device-based care is accelerating. Portfolios that can support stepped-care pathways, rather than isolated touchpoints, will be better aligned with clinical reality and reimbursement dynamics.
- Outpatient and minimally invasive options are gaining commercial attention, not only for patient convenience but also for their alignment with cost-conscious delivery models and shorter recovery expectations.
- Reimbursement architecture remains a gatekeeper. Coding guidance, coverage determinations, and documentation expectations will continue to influence which procedures and products can scale efficiently.
- Market fragmentation creates space for specialization. In a moderately concentrated landscape, targeted clinical niches, distinctive service models, and differentiated access strategies can outperform undifferentiated competition.
The strategic question for leaders is not simply whether the piriformis syndrome market is growing, but how to participate in that growth with the right mix of clinical credibility, commercial execution, and payer readiness. Our research is designed to answer that question with the precision required for high-stakes planning.
Access the Full Intelligence Suite
The market figures, segmentation behavior, competitive dynamics, and regulatory signals highlighted here represent only the opening layer of a much larger analytical framework. The complete Worldwide Piriformis Syndrome Market research goes further, delivering detailed segmentation performance, company-level profiling, forward scenarios, and operational guidance tailored to investment, product development, market-entry, and portfolio- optimization decisions. For executives who need a precise map of where value is being created and how competitive pressure is likely to evolve through 2032, the full report is the essential next step. We invite you to access the complete intelligence suite and equip your organization with the strategic clarity required to act decisively in this evolving market.
For detailed analysis of this topic, please visit the official page: Worldwide Piriformis Syndrome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: WIPS Market to Hit $1.25B in 2025, 14.2% CAGR to $3.16B by 2032
By pmarketresearch, 2026-09-16
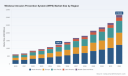
Navigating the Invisible Perimeter: Strategic Imperatives in the Global Wireless Intrusion Prevention System Market
The modern enterprise network perimeter no longer exists as a clearly defined boundary. As organizations accelerate their adoption of hybrid work models, IoT ecosystems, and cloud-native architectures, the wireless layer has become the primary attack surface for sophisticated threat actors. The Worldwide Wireless Intrusion Prevention System (WIPS) Market reflects this fundamental shift in risk geography. Our recent comprehensive analysis indicates that the global market revenue for WIPS solutions reached approximately USD 1,245.5 million in the base year of 2025. Looking forward, the trajectory points toward a significant expansion, with projections estimating the market size to surpass USD 1,420.79 million in 2026 and continuing its ascent to over USD 3,155.06 million by 2032.
This growth is not merely incremental. The compound annual growth rate (CAGR) during the forecast period from 2026 to 2032 is estimated at 14.2 percent. For Chief Information Security Officers (CISOs), procurement leaders, and strategic planners, these figures represent more than just market velocity. They signal a critical inflection point where wireless security transitions from a passive compliance checklist item to an active, intelligence-driven component of the overall security posture. This article serves as an executive primer to our full market research study, outlining the strategic forces shaping the industry, the competitive maneuvers of key market participants, and the regulatory pressures driving adoption.
The Macro-Economic Context of Wireless Security Investment
The expansion of the WIPS market from a valuation of roughly USD 620.45 million in 2020 to the current baseline reflects a maturing recognition of wireless vulnerabilities. During the historical review period from 2020 to 2025, the market demonstrated consistent resilience even amidst broader technology spending fluctuations. The jump from 2024 to 2025 alone indicates a robust demand signal, moving from USD 1,088.3 million to the current 1,245.5 million benchmark.
This trajectory is underpinned by the convergence of several high-stakes dynamics. First, the proliferation of unauthorized and rogue access points remains a persistent threat in dense enterprise environments. Second, the expansion of Wi-Fi 6E and eventual Wi-Fi 7 deployments into the 6 GHz spectrum creates new vectors that require compatible monitoring tools. Third, the financial and reputational cost of a wireless breach continues to escalate, making prevention systems a necessary insurance policy rather than an optional upgrade.
Our forecast data suggests that by 2030, the market will approach USD 2,364.06 million, and by 2032, it will nearly triple the 2025 base size. This growth curve implies that organizations delaying investment in robust wireless intrusion prevention may find themselves technically debt-laden as peers secure their RF spectrums more aggressively.
Regulatory Catalysts and Compliance Pressures
One of the most compelling drivers identified in our research is the tightening regulatory environment. Compliance is no longer just about avoiding fines; it is about maintaining operational eligibility in sectors like finance, healthcare, and government contracting.
In the financial sector, PCI DSS version 4.0 became fully mandatory in April 2025. This update explicitly requires merchants and payment processors to deploy wireless intrusion detection and prevention mechanisms wherever cardholder data is processed. This regulatory mandate effectively forces a significant subset of the retail and hospitality industries to budget for WIPS solutions as a prerequisite for continued payment processing capabilities.
Simultaneously, the healthcare sector faces renewed scrutiny. The U.S. Department of Health and Human Services updated its HIPAA Security Rule guidance in 2025 to include specific recommendations for wireless network monitoring and unauthorized access point detection. Given the sensitivity of protected health information, hospitals and clinic networks are increasingly compelled to integrate WIPS into their broader HIPAA compliance frameworks.
On a broader scale, the European Union's NIS2 Directive, enforced across member states from late 2024, mandates continuous monitoring of network security for operators of essential services. This directive encompasses wireless network perimeters, meaning critical infrastructure providers across Europe must demonstrate active defense mechanisms against wireless intrusions. Furthermore, U.S. Federal agencies operating under FedRAMP and FISMA frameworks have increased their allocation toward wireless monitoring capabilities in IT security budgets, setting a precedent for government contractors to follow suit.
Technological Evolution and Spectrum Dynamics
The technical landscape of WIPS is evolving rapidly alongside regulatory demands. The Federal Communications Commission (FCC) authorization of low-power indoor-only use across the entire 6 GHz band has supported expanded Wi-Fi 6E deployments. While this opens bandwidth for high-speed connectivity, it also requires compatible WIPS solutions capable of monitoring these new spectrum bands for anomalies. Legacy systems designed primarily for the 2.4 GHz and 5 GHz bands may leave blind spots in modern networks.
Additionally, the integration of artificial intelligence and machine learning into wireless security platforms is changing how threats are detected. Traditional signature-based detection is being supplemented by behavioral analytics that can identify rogue devices or anomalous traffic patterns without prior knowledge of specific threat signatures. This shift reduces false positives and allows security teams to focus on genuine risks rather than chasing noise. Our full report details how these technological shifts are influencing vendor roadmaps and customer purchasing criteria.
Competitive Landscape: Key Players and Strategic Moves
The WIPS market is characterized by a mix of specialized security vendors and large networking infrastructure players who embed wireless security into their broader ecosystems. Market concentration data suggests that the top three players hold a significant portion of the market share, with the CR3 percent estimated at 42.15 percent. The top five players collectively command approximately 58.8 percent of the market revenue.
Cisco Systems Inc., headquartered in San Jose, California, remains a dominant force. Their Adaptive Wireless Intrusion Prevention System (aWIPS) is integrated with Catalyst wireless infrastructure and DNA Center. They focus on continuous RF spectrum monitoring, rogue AP detection, and threat containment across Layers 1-3. In April 2025, Cisco announced an expansion of their Meraki cloud management platform with enhanced AI-driven wireless anomaly detection, specifically aimed at strengthening cloud-based WIPS capabilities.
HPE Aruba Networking, based in Santa Clara, California, provides RFProtect WIDS/WIPS designed for monitoring unauthorized access points, clients, and abnormal traffic patterns. Their strategy involves centralized management via Aruba Central integrated into enterprise WLAN infrastructure. Recent technical documentation from early 2025 highlights continued integration and updates to RFProtect for real-time rogue AP and threat monitoring.
Fortinet, Inc., operating out of Sunnyvale, California, delivers WIPS capabilities through its Secure Wireless LAN solutions. They leverage FortiOS for integrated threat detection, prevention, and high-accuracy automation in wireless environments. This integration allows security teams to manage wireless threats alongside their broader Fortinet security fabric.
Worldwide Wireless Acess Point Controller Market
Other notable participants include Extreme Networks, which supplies WIPS functionality in its ExtremeWireless solutions using AirDefense capabilities for continuous protection and policy enforcement. WatchGuard Technologies, based in Seattle, offers cloud-managed WIPS with patented Marker Packet technology in its access points for 24/7 defense against rogue devices and malicious Wi-Fi attacks with low false positives.
Check Point Software Technologies from Tel Aviv integrates wireless threat detection into its Infinity security platform, extending perimeter and network security to wireless environments. NetScout Systems, Inc., based in Westford, Massachusetts, provides wireless intrusion prevention as part of its broader network performance and security portfolio. IBM Corporation offers WIPS-related capabilities through its network security and threat management solutions. Ruckus Networks (CommScope), located in Claremont, North Carolina, includes WIDS/WIPS features in its wireless controllers and access points for rogue device protection and DoS mitigation. Arista Networks, also in Santa Clara, provides WIPS techniques via CloudVision CUE for automated classification of Wi-Fi devices.
Strategic developments in 2024 and 2025 also highlight the importance of government-grade security certifications. In March 2024, the National Security Agency (NSA) released the WIDS/WIPS Annex 2.0.0 for the Commercial Solutions for Classified (CSfC) program. This release supports secure wireless monitoring in government environments, setting a benchmark for security efficacy that influences both public sector and high-security commercial deployments.
Market Structure: Components and Deployment Trends
Understanding how organizations procure WIPS solutions is critical for strategic planning. The market is segmented by components including hardware, software, and services. Our analysis indicates that hardware components continue to hold a substantial share of the revenue mix, reflecting the physical nature of many wireless access points and sensors required for comprehensive coverage. However, the software segment is gaining traction as virtualization and cloud management become preferred methods for deployment and policy orchestration. Services also represent a significant portion of the market, encompassing installation, tuning, and managed security services.
Deployment models are shifting toward cloud-based solutions. Our data shows that cloud-based deployment captures a larger revenue share compared to on-premise solutions. This trend aligns with the broader industry movement toward SaaS and cloud-native security operations. Cloud-based WIPS allows for centralized visibility across distributed enterprise locations, remote offices, and branch networks without the need for on-site maintenance of security appliances. On-premise deployments remain relevant for organizations with strict data sovereignty requirements or specific latency constraints, but the growth momentum favors scalable cloud architectures.
Regional dynamics also play a crucial role in market distribution. North America maintains a leading position in market revenue, driven by high adoption rates in enterprise and government sectors. Europe follows with significant demand fueled by NIS2 compliance and established enterprise infrastructure. The Asia Pacific region represents a high-growth area as digital transformation initiatives accelerate across key economies. Latin America and the Middle East and Africa are emerging markets where infrastructure development and security awareness are beginning to drive demand, though at different maturity levels compared to North America and Europe.
Strategic Implications for Decision Makers
For enterprise leaders evaluating their security roadmap for 2026 and beyond, the WIPS market data offers several key takeaways. First, the 14.2 percent CAGR suggests that the market is expanding faster than general IT security spending in many categories. This implies that wireless security is becoming a priority investment area. Organizations that have treated wireless security as an afterthought to wired network security must recalibrate their budgets.
Second, the concentration of market share among the top five vendors indicates a mature competitive landscape. While this provides stability, it also means that differentiation often comes down to integration capabilities, AI-driven analytics, and ease of management. Procurement teams should evaluate not just the immediate detection capabilities but the long-term roadmap for spectrum monitoring as Wi-Fi 7 and beyond emerge.
Third, the regulatory tailwinds are strong and likely to persist. With PCI DSS, HIPAA, and NIS2 creating mandatory requirements for wireless monitoring, compliance teams should work closely with security architects to ensure that WIPS deployments meet specific regulatory language regarding detection and prevention. Non-compliance risks are not just theoretical; they are operational blockers.
Finally, the shift toward cloud-based management and AI-driven anomaly detection suggests that operational overhead can be reduced while improving detection accuracy. Leaders should seek solutions that minimize false positives, as alert fatigue remains a major challenge in security operations centers. The ability to automate threat containment, such as isolating rogue devices without manual intervention, is becoming a standard expectation rather than a luxury feature.
Worldwide Wireless Intrusion Prevention System (WIPS) Market
Conclusion: The Value of Granular Intelligence
The global Wireless Intrusion Prevention System market is at a pivotal stage. Driven by regulatory mandates, technological advancements in spectrum usage, and the increasing sophistication of wireless threats, the market is poised for sustained growth through 2032. The transition from passive monitoring to active prevention is now the standard, and the integration of wireless security into broader network and security fabrics is essential for resilient operations.
While this overview provides a strategic snapshot of market size, growth rates, competitive players, and regulatory drivers, it only scratches the surface of the available intelligence. Understanding which segments offer the highest ROI, the specific adoption rates across industry verticals, and the detailed pricing dynamics requires deeper analysis. Our full Worldwide Wireless Intrusion Prevention System Market research report contains comprehensive segmentation data, granular regional breakdowns, and detailed company profiles that go beyond these high-level trends. For organizations seeking to build a precise procurement strategy or understand their competitive positioning in this evolving landscape, accessing the complete dataset is essential. The invisible perimeter is expanding, and so too must the depth of your strategic insight.
For detailed analysis of this topic, please visit the official page: Worldwide Wireless Intrusion Prevention System (WIPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Androgen Replacement Therapy Market to Hit $3,591M by 2032 at 5.8% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Wave: Inside the Worldwide Androgen Replacement Therapy Market Outlook 2026-2032
As the global healthcare landscape shifts toward precision endocrinology and expanded therapeutic indications, the androgen replacement therapy (ART) sector stands at a pivotal inflection point. The recent publication of our Worldwide Androgen Replacement Therapy Market research delivers a comprehensive, forward-looking intelligence framework designed specifically to inform enterprise strategy, capital allocation, and commercial execution throughout the 2026-2032 forecast horizon. Drawing on rigorous historical analysis spanning 2020 through base year 2025, the study translates granular market mechanics into actionable decision support for pharmaceutical leaders, investors, and therapeutic development teams.
This introduction outlines the strategic architecture of the full report, demonstrates how macro-level trajectory and structural concentration patterns should reshape executive planning, and previews the operational intelligence embedded across every analytical module. Readers are invited to explore the complete dataset, proprietary sizing tables, and company-level competitive assessments by visiting the source page, where the full intelligence package is available for immediate download.
Macro Trajectory: Reading the Growth Curve Beyond Simple CAGR
The worldwide androgen replacement therapy market has demonstrated resilient expansion across the historical window, with measured revenues progressing from approximately USD 1,850 million in 2020 to a base-year valuation of USD 2,420 million in 2025. Looking ahead, the forecast sequence projects a steady upward trajectory, culminating in a 2032 valuation approaching USD 3,591 million. This evolution reflects a compound annual growth rate of 5.8 percent, a figure that masks significant nuance when examined through the lens of commercial cadence, formulation transitions, and shifting prescribing behaviors.
For executive teams, the strategic implication of this growth profile is not merely revenue forecasting but rather the identification of inflection windows where competitive positioning, regulatory alignment, and product lifecycle timing converge. The forecast period captures a critical bridge between established hypogonadism management and emerging therapeutic applications, making it essential for organizations to calibrate pipeline investments, manufacturing capacity, and go-to-market resources without prematurely locking into static assumptions.
Worldwide Androgen Replacement Therapy Market
The historical volatility observed across recent years underscores the importance of scenario-based planning. Fluctuations in commercial uptake, supply chain recalibration, and evolving safety communication cycles have collectively reshaped demand patterns. The full research deconstructs these movements with transparent methodology, enabling strategists to differentiate between temporary pricing noise and durable structural shifts that warrant long-term capital deployment.
Segment Architecture: Navigating Formulation, Indication, and Regional Dynamics
Understanding how value distributes across therapeutic modalities, clinical indications, and geographic territories is central to effective portfolio strategy. The research examines the androgen replacement ecosystem through three structural lenses: product typology, clinical application, and regional footprint. Each dimension carries distinct commercial characteristics, competitive intensity, and pricing behavior that directly influence market entry timing, asset prioritization, and lifecycle management.
Formulation Pathways and Delivery Innovation
The product landscape spans gel-based systems, injectable platforms, transdermal patches, oral capsules, and implantable or ancillary delivery formats. The research maps the commercial footprint of each category, evaluating formulation advantages, adherence considerations, manufacturing complexity, and reimbursement positioning. Gel-based and injectable modalities continue to anchor a substantial share of total revenue, yet the strategic narrative is increasingly defined by the maturation of oral platforms and the iterative refinement of long-acting delivery systems.
Strategists should note that formulation preference is not uniform across prescriber segments or payer environments. The report dissects how clinical workflows, pharmacy distribution models, and patient convenience factors interact to shape category momentum, providing a practical framework for assessing where incremental innovation or line-extension strategies can generate outsized commercial returns.
Clinical Indications and Therapeutic Breadth
Demand for androgen replacement therapy is anchored primarily in the management of primary and secondary hypogonadism, with an additional segment represented by gender-affirming therapeutic applications. The research quantifies the relative scale of these indication clusters while evaluating how prescribing guidelines, clinical evidence maturity, and payer classification influence adoption velocity. Companies evaluating expansion opportunities must understand not only where current revenue concentrates, but also how clinical narrative shifts and expert consensus evolution can reposition certain formulations within broader endocrine care pathways.
A critical strategic question concerns the boundary between established labeled indications and evolving clinical practice. The report explores how regulatory framing, real-world evidence generation, and specialty society guidance collectively determine which patient populations are accessible under current commercial models, and where near-term label evolution could unlock incremental demand.
Geographic Distribution and Regional Commercial Profiles
The worldwide market reflects a multi-regional architecture with pronounced variation in prescriber density, pricing environment, generic penetration, and reimbursement structure. North American commercial dynamics continue to exert substantial influence on global revenue composition, while European markets operate under distinct procurement and HTA frameworks that shape volume and margin expectations. Asia Pacific, Latin America, and the Middle East and Africa regions present heterogeneous opportunity sets, each requiring tailored market-access strategies, supply chain configurations, and brand-building approaches.
Rather than presenting static regional snapshots, the full study maps how regional growth drivers diverge over the forecast window. This includes analysis of local manufacturing presence, import dependencies, pricing regulation intensity, and the pace at which generic competition compresses branded share. For multinational operators, this regional granularity is essential for prioritizing in-licensing opportunities, localization investments, and partnership structures.
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The androgen replacement therapy market exhibits meaningful concentration among established specialty and generic manufacturers, with the top three participants accounting for approximately 52.4 percent of total revenue and the top five reaching roughly 68.15 percent. This structural concentration indicates that scale advantages, regulatory experience, and entrenched prescriber relationships continue to matter, while also leaving room for focused innovators to capture share through differentiated delivery technologies, oral platform maturation, or niche indication alignment.
Hormone Replacement Therapy (HRT) Market
The research profiles a diverse set of organizations shaping the competitive field. Life science and specialty pharmaceutical leaders including AbbVie Inc., Bayer AG, Endo International plc, Pfizer Inc., Eli Lilly and Company, Novartis AG, and Viatris Inc. maintain significant footprint across branded, specialty, and legacy testosterone portfolios. Their strategic postures differ by geographic emphasis, formulation focus, and reliance on in-house manufacturing versus partnered distribution models.
At the same time, companies such as Lipocine Inc. and Clarus Therapeutics have advanced oral testosterone undecanoate platforms, reflecting broader industry interest in patient-friendly delivery options and oral formulation credibility. The report assesses how these assets interact with existing gel and injectable categories, where clinical differentiation is most defensible, and how payer and prescriber acceptance evolves as oral options gain visibility.
Generic and value-oriented manufacturers including Perrigo Company plc, Sun Pharmaceutical Industries Ltd., Dr. Reddy’s Laboratories Ltd, Teva Pharmaceutical Industries Ltd., and Acerus Pharmaceuticals Corporation represent an additional competitive layer. Their presence influences price erosion patterns, formulary positioning, and the speed at which branded differentiation must be sustained. The study evaluates generic entry timing, bioequivalence pathways, and regional availability as key variables that determine the competitive runway for branded assets in each market.
Regulatory and Clinical Dynamics Shaping the 2026-2032 Window
Regulatory signaling and evolving clinical guidance are not peripheral concerns for this market; they are central drivers of demand expansion, label scope, and commercial risk. The research integrates a series of important regulatory developments that directly affect how companies should plan indications, safety communications, and lifecycle investment.
In February 2025, the FDA updated class-wide labeling for approved testosterone products to incorporate TRAVERSE trial data, removing certain cardiovascular warnings while adding blood pressure-related information. This revision altered the safety narrative that had historically constrained prescribing behavior and influenced payer discussions. The full report evaluates how this labeling adjustment interacts with physician confidence, patient selection criteria, and downstream demand patterns across both branded and generic segments.
During December 2025, the FDA convened an expert panel on testosterone replacement therapy for men to review evidence and clinical use considerations. Panel deliberations of this nature frequently precede label evolution, guideline updates, and shifts in medical education emphasis. The research situates this panel within the broader trend of evidence refinement and explores what changes in expert consensus could mean for indication expansion conversations, marketing claims, and clinical adoption.
A notable development emerged in April 2026, when the FDA encouraged sponsors of approved testosterone replacement therapy products to pursue supplemental new drug applications for a potential new indication addressing low libido in men with idiopathic hypogonadism. The agency also signaled a timeframe for interested holders to initiate contact regarding supplemental applications. This regulatory signal, if acted upon and substantiated through robust clinical programs, could meaningfully broaden the addressable patient population beyond classical structural or genetic hypogonadism cases. The report analyzes the strategic significance of this encouragement, the evidentiary bar that remains, and the commercial implications for companies positioned to move quickly on supplemental development or label-extension planning.
The broader reimbursement context reinforces the importance of indication clarity. Current FDA-approved TRT products are indicated for hypogonadism associated with known structural or genetic causes, while broader idiopathic cases remain outside standard labeled indications or under review for potential expansion. Understanding this boundary is essential for forecasting realistic demand, aligning payer engagement strategies, and prioritizing clinical programs that can support future label evolution without overpromising near-term uptake.
Operational and Supply-Side Realities Driving Market Execution
Commercial strategy in the androgen replacement therapy market cannot be decoupled from upstream supply considerations. The testosterone active pharmaceutical ingredient segment has been valued at approximately USD 1,865 million in 2024, with continued growth projected as demand in hormone replacement therapy and related endocrine applications expands. This upstream dynamic shapes cost of goods exposure, manufacturing capacity planning, and the resilience of supply chains against regional disruptions.
The research addresses how API availability, formulation technology, and manufacturing scale intersect with each product category’s competitiveness. For oral platforms, absorption profiles, formulation stability, and dosing consistency are commercially decisive. For gels and injectables, manufacturing consistency, packaging integrity, and cold-chain or storage requirements influence both cost structure and market access. For implants and ancillary formats, procedural adoption patterns and clinician training needs create distinct go-to-market requirements.
Strategists evaluating capacity expansion, contract manufacturing partnerships, or regional production localization will find detailed discussion of where supply constraints are most likely to emerge and how different product types absorb input cost volatility. This operational lens is critical for organizations seeking to protect margins while scaling commercial presence across multiple territories.
What the Full Report Delivers: A Practical Intelligence Blueprint
This research is structured to translate market complexity into executable intelligence. Beyond the headline sizing and growth trajectory, the full study provides a multi-layered analytical toolkit designed for cross-functional use by corporate strategy, business development, commercial planning, and investment teams.
Key operational elements embedded in the report include:
- Comprehensive historical and forecast sizing with transparent methodology, enabling users to validate assumptions and stress-test internal models against external benchmarks.
- Segment-level analysis across product type, indication, and region that clarifies where value is created, where competition is intensifying, and where whitespace remains for differentiated positioning.
- Competitive profiling of major participants, including commercial footprint summaries, formulation emphasis, and strategic posture that help benchmark relative advantage and identify partnership or acquisition targets.
- Regulatory and clinical timeline mapping that connects FDA labeling updates, expert panel activity, and potential supplemental indication pathways to near-term and mid-term commercial implications.
- Market concentration and share structure analysis that informs pricing strategy, formulary positioning, and the durability of branded differentiation against generic and value-tier competition.
- Practical guidance on how macroeconomic demand drivers, reimbursement dynamics, API supply conditions, and prescriber behavior interact to shape realistic execution scenarios across the 2026-2032 window.
The study is designed to support scenario planning rather than static forecasting. Readers can use the framework to model how different regulatory outcomes, label-extension successes, generic entry timing, and regional reimbursement shifts would alter revenue potential, competitive exposure, and resource prioritization.
Strategic Imperatives for 2026 Enterprise Decision-Making
As organizations enter 2026, the androgen replacement therapy market requires a more dynamic planning posture than historical category maturity might suggest. The convergence of updated safety labeling, expert panel deliberation, and regulatory encouragement for potential new indication pathways creates a period in which early strategic positioning can meaningfully influence share capture and lifecycle optionality.
Several strategic priorities emerge from the macro and structural evidence reviewed in the report:
- Assess which formulation categories align with your organization’s manufacturing strengths and commercial reach, then prioritize investments where adherence advantages, prescriber preference, and payer acceptance reinforce one another.
- Monitor the regulatory trajectory around idiopathic hypogonadism and low libido as a potential indication expansion vector, evaluating whether your pipeline, clinical evidence base, and regulatory capabilities can support timely supplemental activity if the pathway matures.
- Model generic penetration and price erosion across regional markets with realistic timing assumptions, ensuring that branded differentiation strategies are calibrated to the pace at which value-tier competitors reshape formulary dynamics.
- Integrate API supply and manufacturing resilience into commercial planning, particularly where regional demand growth may outpace local capacity or where formulation complexity introduces cost volatility.
- Align medical affairs and payer engagement strategies with the current labeled indication boundary, while preparing evidence-generation and education programs that can support label evolution without relying on assumptions that exceed current regulatory framing.
Conclusion: Turning Market Intelligence into Confident Action
The Worldwide Androgen Replacement Therapy Market research is built for decision-makers who need more than a top-line growth estimate. It offers a structured, evidence-grounded view of how formulation shifts, indication dynamics, regional heterogeneity, regulatory evolution, and competitive concentration interact to shape the commercial landscape through 2032. By connecting historical performance to forward-looking scenario analysis, the study equips organizations to allocate resources with greater precision and to anticipate inflection points rather than react to them.
To explore the complete market sizing tables, region- and segment-level analysis, company competitive profiles, regulatory timeline mapping, and scenario-ready forecasting detail, request the full report through the source page linked below. The complete intelligence package is intended for teams seeking to convert market complexity into executable strategy throughout the 2026-2032 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Androgen Replacement Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metal Fabrication Outsourcing Set for $120.66 Billion by 2032
By pmarketresearch, 2026-09-16
Navigating the Metal Fabrication Outsourcing Landscape: Strategic Intelligence for 2026 and Beyond
The global industrial ecosystem is undergoing a structural transformation. As manufacturers confront rising complexity in supply chains, shifting geopolitical trade dynamics, and the imperative to scale production without bloating fixed assets, metal fabrication outsourcing has evolved from a tactical cost-saving measure into a core strategic capability. PW Consulting's latest Worldwide Metal Fabrication Outsourcing Services Market report offers decision-makers a rigorously validated, forward-looking intelligence framework designed specifically for 2026 planning cycles. This executive summary outlines the strategic architecture of the study, demonstrates how macro and micro market signals intersect, and explains why organizational leaders should treat outsourced fabrication not as a procurement line item, but as a competitive lever.
The report is built on an analytical foundation that tracks historical performance from 2020 through 2025 and projects market trajectories across a seven-year forecast horizon extending to 2032. By anchoring forecasts in verified historical baselines and stress-testing growth assumptions against multiple macroeconomic scenarios, the study delivers the precision required for capital allocation, partnership structuring, and regional capacity planning. The overarching market trajectory reflects sustained expansion, with the sector demonstrating a compound annual growth rate of 5.29 percent across the forecast window. This growth is not linear or isolated; it is shaped by divergent regional maturity curves, evolving service-type demand, and industry-specific procurement behaviors that the full report unpacks in granular detail. Decision-makers who rely on aggregate headlines alone risk misaligning sourcing strategies with the underlying demand architecture. This publication closes that gap.
Why 2026 Demands a Fresh Strategic Lens
The 2026 operating environment presents a confluence of forces that directly reshape how enterprises evaluate, contract, and manage external metal fabrication partners. Raw material benchmarks continue to fluctuate, skilled labor availability remains constrained in key production corridors, and capital allocation priorities are being reallocated toward automation, prefabrication, and digital supply chain integration. These dynamics do not operate in isolation. They interact with broader macro trends, including supply chain diversification, regionalization of manufacturing footprints, and the accelerating energy transition, which collectively influence where capacity is built, which capabilities are outsourced, and how risk is distributed across vendor networks.
The report contextualizes these forces through a structured dynamics framework that separates transient market noise from structural shifts. For instance, pricing signals in ferrous commodities and metallurgical inputs create short-term margin volatility for fabrication service providers, but the longer-term implication lies in how suppliers hedge input risk, adjust pricing models, and invest in yield optimization. Similarly, persistent shortages of skilled welders, machinists, and sheet metal technicians are accelerating adoption of robotic welding cells, automated nesting systems, and digital work-instruction platforms. Enterprises evaluating outsourcing partners must therefore assess not only unit pricing, but also a vendor's automation maturity, workforce retention strategy, and ability to maintain throughput when labor markets tighten.
Reshoring and supply chain diversification further complicate sourcing calculus. Organizations that previously optimized for single-region cost advantages are now recalibrating around resilience, tariff exposure, lead-time predictability, and alignment with local content requirements. The study maps how these considerations influence outsourcing decisions across different industrial verticals and geography clusters, enabling leaders to model trade-off scenarios rather than react to policy or cost shocks after contracts are signed.
Decoding the Market Architecture: Structure Without Noise
A central value of this research lies in its disciplined segmentation logic. Rather than presenting oversimplified top-line figures, the report decomposes the market along three interdependent axes: geographic distribution, service-type capability, and end-use industry demand. This tripartite structure allows executives to diagnose where growth is genuinely converging and where apparent opportunities may be overstated by aggregated reporting.
Geographically, the study examines how demand clusters across major regional corridors, distinguishing between mature markets with stable outsourcing penetration and high-growth regions where capacity expansion, infrastructure investment, and industrial policy are reshaping vendor landscapes. The analysis highlights how regional cost structures, logistics constraints, and local regulatory environments influence the attractiveness of different sourcing models. Instead of isolating single-region percentages, the report frames regional performance in relative terms, helping strategists identify which corridors offer scale, which offer speed, and which offer specialized capability that may justify premium engagement.
On the service-type dimension, the research categorizes outsourced fabrication activity into distinct operational modalities, including machining, cutting, welding, folding and bending, and assembly-plus-other support functions. This breakdown matters because each service type carries different capital intensity, cycle-time profiles, quality-control requirements, and automation potential. A procurement team focused solely on total contract value may overlook the fact that a partner's competitive advantage in precision machining does not automatically translate into cost leadership in structural welding or complex assembly integration. By separating these modalities, the report equips leaders to match service-type strengths with project requirements and to structure multi-vendor ecosystems where each partner plays to a defined capability core.
The end-use industry lens further sharpens strategic relevance. Demand from automotive, aerospace and defense, construction and infrastructure, industrial machinery, energy and power, and other sectors follows distinct procurement rhythms, qualification standards, and volume profiles. High-tolerance aerospace and defense work, for example, places a premium on certified processes, traceability, and engineering collaboration, while construction and infrastructure engagements may prioritize scale, structural component handling, and schedule reliability. Automotive and industrial machinery buyers often balance repeatable precision with cost pressure and changing program cycles. The study's industry-level analysis enables leaders to anticipate where outsourcing demand will intensify, which performance criteria will matter most, and how vendor positioning differs by vertical.
Competitive Landscape: Capability, Positioning, and Strategic Signaling
Market growth is being shaped by a diverse set of participants that range from specialized regional fabricators to global industrial groups and digital manufacturing platforms. The report profiles leading organizations and evaluates how their service portfolios, geographic reach, and recent strategic moves inform broader competitive dynamics. Rather than treating competitors as a static roster, the analysis interprets company activity as signals about where the market is heading and which capabilities are becoming table stakes.
Firms such as Mayville Engineering Company, O'Neal Manufacturing Services, and BTD Manufacturing illustrate the continued importance of domestically anchored, application-focused fabricators that serve heavy equipment, construction, mining, agriculture, and recreational vehicle end markets. Their service emphasis on design support, prototyping, sheet metal fabrication, structural components, and value-added assembly reflects a market where engineering collaboration and sector-specific know-how remain differentiation drivers. Recent capability expansions, including targeted acquisitions and new business wins in metal enclosures and precision components, indicate that scale and service breadth are increasingly intertwined. The research examines how such moves affect pricing power, delivery reliability, and the ability to absorb volatile program demand without sacrificing quality.
Worldwide Metal Fabrication Outsourcing Services Market
Worldwide Intellectual Property Outsourcing Services Market
Global industrial players bring a different strategic posture. Organizations including ThyssenKrupp AG, Caterpillar Inc., Liebherr Group, Nucor Corporation, and XCMG Group operate extensive manufacturing and fabrication networks that span multiple geographies and industrial applications. Their outsourcing-related activities often intersect with internal production optimization, component supply strategies, and large-scale structural or precision fabrication requirements. For buyers, these players can offer integration advantages, program resilience, and access to broad engineering resources. For competitors, they represent both benchmark capabilities and potential channel partners or capacity constraints. The report assesses how such multinational profiles influence regional pricing dynamics, qualification expectations, and the strategic calculus of companies deciding whether to source from specialized independents or broader industrial integrators.
The competitive picture also includes digital-first and on-demand models. Protolabs and Xometry demonstrate how rapid-turn custom sheet metal fabrication, CNC machining, welding access, and marketplace-based supplier routing are reshaping expectations around speed, minimum order flexibility, and transparent quoting. These platforms do not replace traditional fabrication relationships, but they recalibrate baseline expectations for responsiveness and access. The study explores how digital procurement channels interact with traditional outsourcing contracts, where they create incremental value, and where their limitations in complex, high-tolerance, or large-scale projects still require hands-on supplier management.
Market concentration metrics provide additional context. With a relatively fragmented competitive structure at the top, no single vendor or small group of vendors dominates the overall market, which means buyers retain meaningful leverage to curate multi-source strategies and tailor partnerships to specific program needs. At the same time, the presence of capable specialists and large integrated players creates a dynamic environment where consolidation, capability acquisition, and service-line repositioning are likely to continue. The report interprets concentration data not as a static snapshot, but as a starting point for evaluating partnership risk, negotiation posture, and long-term sourcing architecture.
Inside the Report: Practical Intelligence for Operating Decisions
This research is designed for immediate operational application. Beyond macro-level forecasting, the report delivers structured analytical modules that support sourcing strategy, capability evaluation, risk assessment, and investment prioritization. The study integrates historical performance data, forward projections, service-type and industry-level demand mapping, regional dynamics, competitive profiling, and a set of qualitative market drivers that shape negotiation and contracting behavior.
Practitioners will find actionable frameworks for identifying which outsourcing capabilities are becoming commoditized and which remain differentiated by engineering rigor, certification depth, scale, or automation maturity. The analysis helps leaders determine where to consolidate spend for leverage, where to diversify for resilience, and where to pursue long-term partnerships that include joint process improvement or capacity planning. It also provides the context needed to interpret vendor proposals critically, especially when pricing, lead times, and capability claims diverge across suppliers.
A distinctive feature of the report is its integration of market dynamics with real-world operational considerations. Input cost trajectories, labor availability, automation adoption, energy-transition-driven investment, and supply chain restructuring are each evaluated for their implications on vendor behavior and buyer decision-making. By connecting these drivers to sourcing outcomes, the study enables executives to move beyond static price comparisons and evaluate total value, including reliability, quality consistency, engineering support, and the ability to adapt as program specifications evolve.
Translating Intelligence into 2026 Action
For organizations preparing for 2026, the strategic question is no longer whether to outsource metal fabrication, but how to structure outsourcing relationships so they reinforce broader business objectives. The report supports that transition by converting market intelligence into decision-ready guidance across several priority areas.
- Align outsourcing strategy with supply chain reconfiguration plans, including regional diversification, tariff exposure management, and lead-time reliability targets.
- Evaluate vendor capabilities against project-specific service-type requirements, recognizing that machining, cutting, welding, forming, and assembly each carry distinct operational risk and quality profiles.
- Incorporate automation maturity and workforce stability into supplier selection criteria, especially where skilled labor constraints could affect throughput or consistency.
- Use industry-level demand insights to anticipate qualification requirements, volume patterns, and engineering collaboration expectations in sectors such as automotive, aerospace and defense, construction and infrastructure, industrial machinery, and energy and power.
- Identify where digital and on-demand models can complement traditional partnerships for rapid prototyping, low-volume production, or intermittent demand spikes without compromising the integrity of core supply agreements.
- Monitor competitive and structural signals, including capability acquisitions, service-line expansions, and concentration trends, to anticipate shifts in pricing dynamics and vendor availability.
The study also provides the analytical discipline needed to separate short-term cost movements from durable structural advantages. A vendor offering aggressive unit pricing may not be the best long-term partner if its process controls, engineering support, or automation roadmap do not align with future program demands. Conversely, a partner with stronger capability depth may justify a premium when total cost of ownership, schedule certainty, and reduced rework are factored in. The report helps leaders make those trade-offs explicit.
Positioning for the Next Phase of Market Evolution
The worldwide metal fabrication outsourcing services market is advancing through a period of capability redefinition. Growth is being shaped not only by demand expansion, but also by how efficiently organizations can access specialized fabrication capacity, integrate external partners into product development cycles, and adapt to changing input costs, labor conditions, and geopolitical realities. The firms that succeed in this environment will be those that treat outsourcing as a design variable in their broader operating model rather than a reactive procurement fix.
PW Consulting's Worldwide Metal Fabrication Outsourcing Services Market report provides the evidentiary foundation required to make that shift with confidence. It combines rigorous forecasting, multi-axis segmentation, competitive intelligence, and market-dynamics analysis into a single strategic reference. The result is a resource that supports informed negotiation, smarter vendor selection, and more resilient sourcing architecture as enterprises move through 2026 and beyond.
To access the complete dataset, detailed segmentation breakdowns, full company profiles, and the underlying analytical models that support these conclusions, request the full report through the PW Consulting research portal. The executive view presented here is intended to establish strategic context and demonstrate the depth of the analysis; the complete study delivers the granular intelligence necessary for precise planning, benchmarking, and execution.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Fabrication Outsourcing Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plexiform Neurofibromas Market Reaches $720M in 2025, 17.95% CAGR to $2.28B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Plexiform Neurofibromas Treatment Market: Navigating the 2026 to 2032 Opportunity Horizon
Executive Overview
Plexiform neurofibromas represent one of the most complex and clinically challenging manifestations of neurofibromatosis type 1, a genetic disorder that affects more than a quarter million individuals across major global markets. For decades, surgical resection remained the primary intervention, yet the infiltrative nature of these tumors often rendered complete removal impossible without significant morbidity. The therapeutic paradigm has shifted decisively in recent years, driven by the emergence of targeted small molecule inhibitors that address the underlying RAS-MAPK pathway dysregulation. This transformation has created a high-growth market segment that demands rigorous strategic analysis, precise forecasting, and a clear understanding of competitive positioning.
This market research study provides a comprehensive evaluation of the worldwide plexiform neurofibromas treatment market, offering decision-makers the granular intelligence required to allocate resources, shape pipeline strategies, and anticipate regulatory shifts. The analysis spans historical performance from 2020 through the base year of 2025 and extends a detailed forecast horizon to 2032, capturing the inflection points that define this rapidly evolving landscape.
Macro Market Dynamics and Growth Trajectory
The global market for plexiform neurofibromas treatments has undergone a profound expansion over the past half-decade. Historical revenue data reveals a trajectory that begins at 42.15 million USD in 2020, accelerates sharply to 109.83 million USD in 2021, and continues its upward momentum through successive valuation milestones reaching 210.27 million USD in 2022 and 404.65 million USD in 2023. By the base year of 2025, the market had scaled to 720.0 million USD, reflecting the compounding effect of regulatory approvals, expanded labeling, and increasing clinical adoption of targeted therapies.
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Looking forward, the forecast period from 2026 to 2032 projects sustained and robust growth. The market is expected to reach 896.65 million USD in 2026, climbing steadily through intermediate forecast years to 1,289.4 million USD in 2028, then accelerating further toward 1,584.17 million USD by 2029. The compound annual growth rate across the full forecast window is calculated at 17.95 percent, underscoring the structural momentum behind this therapeutic category. The end-state valuation for 2032 is projected at 2,284.32 million USD. These figures illustrate a market that is not merely growing but fundamentally maturing as addressable patient populations expand and reimbursement frameworks adapt to support high-cost targeted interventions.
Throughout this narrative, all monetary values are expressed in United States dollars and measured in millions. Readers seeking the precise year-by-year breakdowns, sensitivity analyses, and scenario modeling that underpin these trajectories will find the complete dataset within the full report, where every assumption and methodological choice is transparently documented.
Segmentation Architecture and Addressable Patient Pools
Understanding how revenue distributes across therapeutic modalities, patient demographics, and geographic regions is essential for strategic planning. The analysis segments the market along three critical dimensions that reflect both clinical reality and commercial opportunity. By therapy type, targeted molecular inhibitors dominate the revenue landscape, with surgical intervention and chemotherapy-based approaches comprising the remaining share. By patient demographic, pediatric populations represent a substantial portion of the addressable market, while adult patients form a dynamically growing cohort as diagnostic awareness improves and expanded indications gain regulatory traction. Regional analysis further delineates market density across North America, Europe, Asia Pacific, and Rest of World, highlighting variations in treatment access, clinical infrastructure, and pricing environments.
These segmentation splits are not merely descriptive; they reveal where investment, partnership, and commercialization efforts should be concentrated. The detailed percentage allocations, absolute values for each category, and the interplay between demographic shifts and regional adoption curves constitute the analytical core of the study. Accessing the complete segmentation tables and cross-referenced breakdowns will allow stakeholders to pinpoint the highest-probability growth pockets and calibrate their market entry or expansion strategies accordingly.
Worldwide Plexiform Neurofibromas Treatment Market
Competitive Landscape and Key Player Profiles
The plexiform neurofibromas treatment market is characterized by a highly concentrated competitive structure. Market concentration metrics indicate that the top three firms command 88.4 percent of total revenue, while the top five entities collectively represent 94.15 percent. This oligopolistic dynamic reflects the regulatory and clinical barriers associated with developing targeted inhibitors for rare neurofibromatosis indications, as well as the significant clinical data requirements imposed by health authorities worldwide.
Two companies stand at the forefront of this market and are profiled in depth within the research. AstraZeneca Pharmaceuticals LP, operating in collaboration with Merck & Co., Inc., markets Koselugo, known generically as selumetinib, an oral MEK inhibitor approved for pediatric patients one year of age and older as well as adults with neurofibromatosis type 1 who present with symptomatic, inoperable plexiform neurofibromas. SpringWorks Therapeutics, Inc. markets Gomekli, or mirdametinib, an oral MEK1/2 inhibitor approved for adult and pediatric patients two years and older with symptomatic plexiform neurofibromas that are not amenable to complete resection. Both products have secured pivotal regulatory milestones that reshaped treatment standards and established the MEK inhibition pathway as the cornerstone of modern pharmacotherapy for this indication.
Beyond these market leaders, the competitive field includes emerging candidates and development-stage assets that may influence future share dynamics. The report includes detailed competitive profiling that examines product positioning, clinical differentiation, geographic rollout strategies, and anticipated head-to-head competition. Stakeholders evaluating partnership opportunities, licensing deals, or market entry timing will benefit from the structured comparison of strategic capabilities and pipeline trajectories provided in the full analysis.
Regulatory and Reimbursement Dynamics Shaping 2026
The period surrounding 2026 has been defined by a series of high-impact regulatory actions that directly expand the patient populations eligible for targeted treatment. In January 2026, the FDA expanded its approval of Koselugo granules and capsules to include pediatric patients one year of age and older with neurofibromatosis type 1 and symptomatic, inoperable plexiform neurofibromas. Concurrently, the European Commission approved the therapy for children aged one to less than seven years, as well as for patients experiencing swallowing difficulties, broadening the addressable demographic across key international markets. In November 2025, the FDA had already approved Koselugo for adults with neurofibromatosis type 1 and symptomatic, inoperable plexiform neurofibromas based on the KOMET Phase III trial, setting the stage for continued adult market penetration.
Further extending global reach, AstraZeneca announced in March 2026 that Koselugo received regulatory approval in Canada for adult patients meeting the same clinical criteria, supported by KOMET Phase III data that demonstrated a 20 percent objective response rate. These sequential approvals illustrate a deliberate regulatory strategy that incrementally widens labeling, enhances payer confidence, and accelerates real-world utilization.
On the competing side, SpringWorks Therapeutics achieved FDA approval in February 2025 for Gomekli in adult and pediatric patients two years and older with symptomatic plexiform neurofibromas not amenable to complete resection, based on the ReNeu Phase IIb trial. The presence of two approved targeted therapies specifically indicated for symptomatic, inoperable neurofibromatosis type 1-associated plexiform neurofibromas in their respective approved age groups has established a new standard of care and intensified the focus on differentiation through tolerability, dosing convenience, and long-term safety data.
Additional industry dynamics continue to reshape the environment. The FDA granted Fast Track designation to PAS-004, a next-generation macrocyclic MEK inhibitor developed by Pasithea Therapeutics, for the treatment of neurofibromatosis type 1-associated plexiform neurofibromas causing significant morbidity. Fast Track status signals regulatory receptivity to innovation in this space and may accelerate development timelines for next-wave entrants. Together, these regulatory and reimbursement developments create a market environment where label expansion, patient identification, and access optimization are decisive factors in capturing growth.
Real-World Clinical Considerations and Market Access Realities
While regulatory approvals unlock theoretical market potential, commercial realization depends on execution across clinical, reimbursement, and service delivery dimensions. Targeted therapies for plexiform neurofibromas require careful patient selection, monitoring for adverse events, and coordination among pediatric neurologists, oncologists, genetic counselors, and surgical specialists. The complexity of the care pathway influences how quickly new indications translate into prescribing behavior, particularly in regions where multidisciplinary tumor boards and specialized neurofibromatosis centers are limited.
Reimbursement frameworks are equally critical. Payers evaluate the cost-effectiveness of oral targeted inhibitors relative to the historical burden of repeated surgical procedures, surveillance imaging, and quality-of-life deterioration associated with tumor progression. As health technology assessment bodies gather real-world evidence and long-term outcome data, pricing negotiations, managed entry agreements, and formulary positioning will determine the pace at which targeted therapies achieve broad utilization. Market participants that invest early in robust health economics and outcomes research, patient support programs, and clinician education are better positioned to secure favorable access and sustain share.
The report delves into these operational realities with granular attention to regional access policies, pricing structures, and the clinical adoption curve. The precise data underpinning these assessments, including scenario-based market access modeling and detailed indication-level uptake estimates, are reserved for the complete study, where they can be directly applied to pricing strategy and launch planning.
Strategic Implications for Decision-Makers in 2026
Companies operating in or evaluating this market face a set of interconnected strategic questions. First, how should pipeline investments be prioritized given the dominance of MEK inhibition and the emergence of next-generation macrocyclic candidates? Second, where should commercialization resources be allocated to maximize return on launch investments across regions with varying regulatory maturity and reimbursement readiness? Third, what partnership structures, whether co-promotion, licensing, or combination development, offer the fastest route to expanded patient reach without overextending internal capability?
The answers depend on a clear view of market size evolution, segment-specific growth rates, competitive vulnerabilities, and the regulatory calendar. The forecast growth to 2,284.32 million USD by 2032 is not simply a top-line number; it reflects the cumulative effect of expanded pediatric and adult indications, deeper penetration in concentrated markets, and the gradual adoption of targeted therapy in regions where access has historically been constrained. Companies that align their strategy with these structural drivers, rather than relying on static market snapshots, will be better equipped to capture disproportionate value.
The study provides decision-makers with the framework to evaluate entering via asset acquisition, expanding through geographic rollout, or defending position through differentiated clinical data and service capabilities. Each path requires specific intelligence about competitor intentions, payer behavior, and the timing of label expansions. The detailed scenario analyses, competitive response simulations, and indication-level revenue projections available in the complete report translate high-level trends into actionable strategic choices.
Why Access the Full Study Now
Partial visibility into a market of this magnitude and complexity carries real risk. Aggregate figures and headline growth rates can mask important divergences between therapy types, demographic cohorts, and regional markets. Competitive concentration may appear stable on the surface while underlying regulatory approvals and pipeline developments are actively reshaping future share distribution. Without the full dataset, strategic plans risk being miscalibrated to the true shape of opportunity.
The complete worldwide plexiform neurofibromas treatment market research report offers a full suite of analytical tools: year-by-year market size and forecast tables from 2020 through 2032, detailed segmentation splits with absolute and relative values, regional and demographic growth drivers, competitive profiles that connect product strategy with regulatory milestones, and assessment of industry context factors such as Fast Track designations and reimbursement eligibility. Every projection is supported by documented assumptions, methodological transparency, and scenario flexibility that allow readers to test sensitivities relevant to their own portfolios.
Accessing the full study equips executives, strategy teams, and investment decision-makers with the precise intelligence needed to time market moves, prioritize territories, benchmark competitive threats, and build defensible growth plans for the 2026 to 2032 window. The detailed segmentation data, company-specific revenue estimates, and projection models that underpin the narrative presented here are available in the complete report, where they can be immediately integrated into strategic planning workflows.
For detailed analysis of this topic, please visit the official page: Worldwide Plexiform Neurofibromas Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Customs Brokerage Hits $16.25B in 2025, Forecast 6.4% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the New Trade Frontier: Strategic Intelligence for the Customs Brokerage Services Market 2026–2032
The Strategic Imperative for 2026 Decision-Makers
Global trade flows are undergoing a structural transformation. Between 2020 and 2025, the worldwide customs brokerage services sector expanded from a revenue base of approximately 11,850 million USD to 16,250 million USD, reflecting an annualized growth trajectory that accelerated sharply in the post-pandemic recovery window. As we enter 2026, the market is projected to cross 17,238 million USD, and our forecast model maps a sustained compound annual growth rate of 6.4 percent through 2032, culminating in a market size exceeding 25,086 million USD. For executives navigating tariff realignments, regionalization of supply chains, and automated compliance mandates, these aggregate figures are only the starting point. What separates strategic leaders from reactive adopters is the ability to decode where growth concentrates, which service models capture margin, and how regulatory modernization reshapes operating economics. This intelligence brief introduces our newly published Worldwide Customs Brokerage Services Market study—a decision-grade reference designed to convert macroeconomic momentum into actionable competitive advantage.
Market Architecture: Scale, Segmentation Logic, and Concentration Signals
The customs brokerage landscape is no longer a commoditized clearance utility. It is a value-adding intermediary layer that sits at the intersection of logistics execution, regulatory interpretation, and digital trade infrastructure. Historical data from 2020 through 2025 demonstrates consistent expansion, but the composition of that expansion reveals strategic asymmetry. Revenue generation is distributed across geographical corridors, service capabilities, and end-user verticals, each carrying distinct risk-return profiles. Rather than treating the market as a monolithic pool, effective strategy requires understanding how distinct demand clusters behave under shifting trade policy, freight volatility, and technology adoption cycles.
Geographically, the market spans mature trade hubs and high-velocity emerging corridors, with aggregate regional contributions reflecting both historical trade density and evolving nearshoring dynamics. In terms of service models, the largest revenue cluster continues to be anchored by transactional customs clearance, while advisory and compliance services and trade management software represent structurally higher-margin, stickier engagement models. End-user demand is diversified across manufacturing, retail and e-commerce, automotive, healthcare, and other sectors, each exposing brokers to different customs code complexities, valuation rules, and documentation cadences.
Importantly, the competitive field remains relatively fragmented at the top. Our concentration analysis indicates a top-three share of approximately 18.45 percent and a top-five share of roughly 27.3 percent. This fragmentation is strategically meaningful: it signals room for differentiation through specialization, technology-enabled service design, and regional depth, while also warning that scale alone does not guarantee pricing power. In a market where compliance intensity is rising and client expectations are shifting toward integrated visibility, share acquisition increasingly depends on capability stacking rather than volume alone.
Recent Dynamics: Regulatory Modernization, Compliance Economics, and Technology Adoption
The operating environment for customs brokerage firms has entered a phase of accelerated regulatory and technological recalibration. Two forces are particularly consequential for 2026 planning. First, regulatory modernization is reshaping both cost structures and process expectations. U.S. Customs and Border Protection has continued to advance the Customs Automated Payment and Entry system, with recent evaluations expanding refund scenarios and system capabilities for brokers and importers. Alongside this, the National Customs Brokers & Forwarders Association of America has highlighted new CBP procedures for updating Trade Account Owner information on existing ACE Portal accounts, signaling a compliance administration layer that requires proactive preparation. In parallel, CBP modernized customs broker regulations under 19 CFR 111 to optimize resource allocation and update compliance requirements, reinforcing a trajectory in which documentation accuracy, system readiness, and audit responsiveness are becoming core differentiators.
Second, compliance economics are becoming more visible and more demanding. Industry operating cost analysis indicates that customs brokerage firms allocate roughly 1,500 USD per month for regulatory compliance costs covering licensing and ongoing filings. On top of that, CBP set the 2026 annual customs broker permit user fee at 185.38 USD per national permit, with payment due by January 30, 2026. These are not marginal line items; they influence margin planning, service pricing, and the relative attractiveness of compliance automation. At the same time, brokers are increasingly adopting AI-powered compliance software and automated document verification to manage regulatory complexity, reduce manual exception handling, and improve throughput. The firms that treat technology as a compliance multiplier—not merely a back-office efficiency tool—are positioned to convert regulatory pressure into service differentiation.
Policy signals extend beyond the United States. The OECD Services Trade Restrictiveness Index for logistics customs brokerage services recorded notable policy changes in 2025, including increases in Ireland and the United States. For multinational operators and cross-border traders, this underscores the importance of monitoring regulatory restrictiveness as a variable that can alter route selection, entity structure, and service delivery models. In short, customs brokerage is no longer a static clearance function; it is a dynamic compliance-and-technology battlefield.
Competitive Landscape: Integrators, Specialists, and the Consolidation Undercurrent
The market is populated by a diverse set of incumbents, ranging from global logistics integrators to dedicated brokerage specialists. The strategic tension is clear: scale players leverage multimodal networks, global forwarding footprints, and platform ecosystems to bundle brokerage into broader supply chain offerings, while focused brokers compete on depth of customs expertise, client intimacy, and specialized trade compliance advisory. Both models can win, but they require different operating playbooks.
Worldwide International Freight Forwarding Services Market
Among the scale-oriented integrators, several global logistics and transportation enterprises embed customs brokerage within broader service portfolios. UPS Supply Chain Solutions delivers brokerage as part of integrated supply chain solutions, including entry filing, compliance management, and global clearance across air, ocean, and ground shipments. FedEx Trade Networks emphasizes efficient clearance, documentation, and regulatory compliance for international shipments through a dedicated brokerage arm. DHL Global Forwarding positions worldwide brokerage and clearance within its global forwarding network, leaning on compliance discipline, digital tools, and end-to-end trade management. Kuehne + Nagel, DB Schenker, GEODIS, DSV, and A.P. Moller – Maersk similarly integrate brokerage capabilities into freight forwarding, ocean logistics, and supply chain optimization portfolios, using network breadth to serve multinational clients with complex routing and multimodal requirements. C.H. Robinson Worldwide supports customs brokerage through its Navisphere platform, backed by more than 800 cross-border specialists and over 100 licensed customs brokers, illustrating how digital visibility and brokerage expertise can be paired at scale.
At the same time, dedicated brokerage providers continue to demonstrate the value of specialization. Expeditors International of Washington represents customs brokerage as a core offering, with licensed brokerage operations handling import/export clearance, compliance, and related trade services worldwide, forming a substantial share of its revenue base. Livingston International operates as a leading North American dedicated customs brokerage provider, serving tens of thousands of clients with brokerage, global trade management, compliance consulting, and freight solutions. GHY International specializes exclusively in customs brokerage and global trade services for North American companies engaged in international trade, drawing on more than a century of focused expertise. A.N. Deringer emphasizes compliance-oriented brokerage services, with active engagement in CBP system developments such as CAPE for refunds and entry processing.
The competitive logic here is not simply size versus specialization; it is integration depth versus jurisdictional fluency. Integrators gain advantage when clients want a single point of accountability across transport modes and trade lanes. Specialists gain advantage when clearance complexity, audit exposure, and compliance advisory requirements make domain expertise the primary purchasing criterion. Our study maps how these competing value propositions perform across regions and end-user segments, allowing leadership teams to benchmark their positioning against the operational models that are gaining traction in 2026.
Worldwide Customs Brokerage Services Market
Market Consolidation and M&A As a Strategic Signal
Recent deal activity reinforces the view that technology integration and capability expansion are reshaping industry structure. In April 2026, Zonos acquired Evolve Trade Services to embed customs brokerage capabilities directly into its cross-border operating system. This type of transaction reflects a broader pattern: platforms seeking to turn brokerage from an external dependency into an integrated control point within the buyer journey and fulfillment workflow. For both brokers and traders, the implication is significant. As clearance capabilities become embedded in e-commerce enablement, pricing, and landed-cost computation tools, the brokerage value proposition will increasingly be judged on speed, data continuity, and system interoperability—not just per-entry service quality.
This consolidation undercurrent matters for more than valuation narratives. It influences partner selection, outsourcing strategy, and the design of internal trade compliance functions. Organizations that rely on fragmented service providers may find themselves exposed to coordination friction, while those that consolidate trade services around platforms with integrated brokerage may gain visibility at the expense of flexibility. Understanding which model prevails in which segment is essential for procurement, operations, and trade compliance leaders.
What the Study Delivers: Practical Intelligence for Execution
The Worldwide Customs Brokerage Services Market study is structured to give strategy, operations, and trade compliance teams a usable map of the market rather than a static snapshot. The analysis is anchored in historical performance from 2020 through 2025 and extends a detailed forecast through 2032, enabling scenario planning around growth traction, service demand, and regional opportunity. Beyond aggregate sizing, the study breaks down the market across the dimensions that most influence strategic choice: regional corridors, service-type economics, and end-user demand profiles. This multi-axis view helps organizations identify where to invest, where to differentiate, and where to defend.
Equally important, the report situates market data within the operational realities that shape execution. It examines how regulatory modernization, compliance costs, permit economics, and system modernization affect brokerage operating models. It also traces technology adoption patterns, including the role of AI-enabled compliance software and automated document verification, as well as the increasing importance of digital trade management platforms. By connecting market sizing to operating conditions and competitive behavior, the study supports practical decisions on pricing, service design, partnership strategy, geographic coverage, and technology investment.
The competitive analysis component goes beyond company descriptions to interpret how major players are competing: through network integration, platform-enabled visibility, specialized compliance advisory, and targeted acquisitions. Combined with recent developments such as CAPE system updates, ACE Portal account administration changes, and the 2026 broker permit fee schedule, the study converts regulatory and industry events into decision-relevant context. For executives who need to align trade strategy with supply chain resilience, cost discipline, and compliance risk, that context is not optional; it is the basis for credible planning.
Why This Intelligence Matters for 2026 and Beyond
The 6.4 percent CAGR projected through 2032 indicates that customs brokerage services will remain an important and growing interface between global commerce and regulatory systems. But growth alone does not create advantage. Advantage is created by anticipating how service demand will shift across segments, how compliance automation will reshape cost structures, and how integration versus specialization will determine competitive outcomes in each geography and end-market. The firms and trading organizations that treat customs brokerage as a strategic capability—rather than a transactional necessity—will be better positioned to manage tariff exposure, clearance delays, audit risk, and cross-border uncertainty.
This study is designed to support that shift. It provides the macro framework, segment logic, competitive context, and regulatory signals required to build a forward-looking trade services strategy. To access the full segmentation detail, regional and service-type analysis, end-user breakdowns, and complete competitive profiles, we invite decision-makers to review the complete report at the source page. The full intelligence package is built to translate market momentum into concrete choices across service design, geographic focus, technology investment, and partnership strategy for the 2026–2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Customs Brokerage Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence Brief: The Worldwide 2'-Fucosyllactose (2'-FL) Market Trajectory Through 2032
The global landscape for human milk oligosaccharides has entered a definitive phase of commercial maturation. As scientific consensus solidifies around the functional benefits of 2'-Fucosyllactose (2'-FL), the ingredient has transitioned from a niche innovation to a foundational component in early-life nutrition and functional wellness. Our latest comprehensive study, the Worldwide 2'-Fucosyllactose Market Report, provides the analytical rigor required to navigate this high-growth environment. This briefing outlines the strategic contours of the market, emphasizing the decision-making leverage available to stakeholders who align their portfolios with verified data rather than conjecture.
Macro Market Trajectory and Growth Velocity
The economic signal coming out of the 2'-FL sector is unambiguous. Following a period of infrastructure build-out and regulatory clearance, the market has demonstrated consistent value acceleration. Historical data captured in our analysis shows a clear upward curve from the base year through the current period, reflecting both volume uptake and premium pricing dynamics in advanced applications. Looking forward, the forecast period extending to 2032 projects a robust compound annual growth rate of 14.5 percent.
This trajectory is not merely incremental; it represents a structural expansion of the addressable market. By the end of the forecast horizon, the global revenue pool is expected to scale significantly beyond the 2025 baseline. For strategic planners, this implies that the window for establishing market presence is narrowing. The growth curve suggests that demand generation will increasingly be driven by reformulated standard-of-care products rather than novel introductions, shifting the competitive battlefield toward supply reliability, cost efficiency, and regulatory fluency. Companies that secure their positioning now will be better insulated against the margin compression that typically accompanies late-stage category expansion.
Worldwide 2'-Fucosyllactose (2'-FL) Market
Production Architectures and Segmentation Realities
The supply side of the 2'-FL market is defined by a divergence in production methodologies, each carrying distinct implications for cost structure, scalability, and purity profiles. The market is currently anchored by fermentation-based production, which has captured the majority of commercial volume due to its alignment with natural-origin labeling trends and its scalability through engineered microbial strains. Chemical synthesis, while representing a smaller share of the total output, maintains strategic relevance in specific high-purity or specialized research contexts.
Lactose serves as the primary substrate for most microbial fermentation processes, with engineered strains providing the necessary fucosyltransferase activity to drive conversion. This technical foundation means that supply chain resilience is increasingly tied to the stability of lactose sourcing and the proprietary efficiency of fermentation yields. The segmentation between production types is not just a technical distinction; it is a commercial differentiator that influences customer procurement criteria, particularly in regions where origin labeling and clean-label positioning carry significant price premiums.
From an application perspective, the demand profile remains heavily weighted toward infant formula, which continues to absorb the vast majority of commercial volumes as manufacturers integrate 2'-FL into both standard and premium formulations. However, the diversification into dietary supplements and functional foods and beverages is gaining traction, signaling a broader utility narrative that extends beyond early-life nutrition. This expansion is critical for companies seeking to balance volume concentration risks. The ability to pivot supply toward supplement and functional food channels as infant formula margins evolve will be a key determinant of long-term portfolio resilience.
Geographical Demand and Regional Imperatives
The spatial distribution of 2'-FL demand reflects the varying maturity of regulatory frameworks and consumer awareness across key territories. North America and Europe collectively represent the largest demand centers, driven by established approval pathways, high procurement standards, and a consumer base that is already educated on the benefits of HMO supplementation. These mature markets demand consistent quality, comprehensive documentation, and supply continuity that only well-capitalized producers can reliably deliver.
Asia Pacific presents a different strategic calculus. While its current absolute volume is smaller than the Western centers, the region is characterized by rapid regulatory evolution and aggressive formulation activity in key national markets. The entry of new production capacities and the progressive clearance of additional strains are unlocking demand that was previously constrained by compliance uncertainty. Latin America and the Middle East and Africa, while representing smaller shares of the current global volume, are emerging as watchpoints for future growth. In these regions, the pace of adoption will likely be dictated by the speed of local regulatory harmonization and the degree to which regional manufacturers can access globally approved supply streams without prohibitive import barriers.
For multinational brands and ingredient suppliers, the geographical segmentation underscores the need for a tiered market entry strategy. Pouring equal resources into every territory is inefficient. The data suggests that prioritization should follow the gradient of regulatory readiness and formulation activity, with heavier investment in regions where approvals are fully active and consumer pull is demonstrable, while maintaining a surveillance posture in territories where approvals are in progress.
Competitive Landscape and the Consolidation Imperative
The 2'-FL market is not a level playing field. Market concentration metrics indicate a moderately consolidated environment, where a core group of global players controls a substantial portion of the supply and intellectual property landscape. This concentration is a function of the capital intensity required to build compliant fermentation facilities, the time lag associated with regulatory approvals across multiple jurisdictions, and the patent thickets that protect key production strains and formulation technologies.
Leading figures in this landscape include dsm-firmenich, which offers its GLYCARE 2FL line across multiple grades tailored for infant formula, baby and kids nutrition, and digestive health applications. Their portfolio includes specialized variants designed to meet specific allergen and religious compliance requirements, reflecting a market where granularity in product specifications translates directly into customer retention. Novonesis, formerly Chr. Hansen, brings extensive commercialization history and a broad patent estate to its MyOli 2'-FL offering, frequently positioning the ingredient in combination with probiotic solutions to deliver synergistic gut health narratives.
In Europe, the partnership between Wacker Chemie AG and BENEO exemplifies the strategic alignment of production and commercialization expertise. Wacker's microbial fermentation capabilities, combined with BENEO's distribution and formulation knowledge, enable a streamlined path to market for purified 2'-FL powder in infant nutrition applications. This type of alliance is indicative of a broader trend where production specialization and commercial reach are being deliberately decoupled and then re-linked through partnership structures to accelerate time-to-revenue.
In the Asia-Pacific sphere, Kyowa Hakko Bio, a Kirin Holdings company, has established a production footprint in Thailand and has been methodically securing regional approvals, including clearance from India's FSSAI as a food ingredient. Their approach highlights the importance of staging regulatory wins in high-population markets to build a foundation for volume growth. Meanwhile, IFF has leveraged its global regulatory affairs infrastructure to secure approvals in stringent markets including China, where its 2'-FL HMO has been cleared for use in infant formula, follow-up formula, and special medical purposes. FrieslandCampina Ingredients continues to advance its Aequival trademarked 2'-FL, with regulatory progress such as MARA approval in China for its production strain, signaling a concerted push into the high-value Chinese infant nutrition market.
The strategic implication of this landscape is clear. New entrants or smaller players cannot compete on breadth alone. They must either specialize in a high-margin niche, secure a distinctive production advantage, or align with a partnered commercialization channel. For buyers, the concentration of supply among proven, compliant manufacturers reduces procurement risk but also limits negotiating leverage. Diversifying supplier relationships while maintaining quality thresholds is therefore a prudent risk management practice.
Human Milk Oligosaccharides (HMO) Market
Regulatory Fluidity as a Strategic Variable
Regulation remains the single most powerful variable shaping the pace and geography of 2'-FL adoption. The period covered by our report has been marked by a series of approvals and clarifications that are progressively removing the compliance fog that previously slowed adoption. In China, the National Health Commission has approved additional production strains for 2'-fucosyllactose, with application scope and usage levels aligning with established announcements, effectively widening the pool of eligible suppliers and formulations.
In Europe and the United Kingdom, approvals have been granted for dsm-firmenich HMO ingredients, including mixtures containing 2'-FL, with effective dates spanning mid-2024. These approvals not only validate the safety profile of specific product grades but also set precedents that smooth the path for related formulations. The recent global launch of 2'-FL produced via precision fermentation in Europe, commercialized by BENEO following partnership with Wacker Chemie AG, demonstrates how regulatory clearance and commercial execution can converge to create new supply momentum in a key region.
In Asia, Kyowa Hakko Bio's receipt of FSSAI approval in India marks a milestone as the first HMO from the company cleared in the Indian market, opening a demographic base with significant growth potential. Additional regulatory progress, including dsm-firmenich's approval of GLYCARE 2FL in Indonesia for flavored liquid milk drinks for children above three years, illustrates how approvals are gradually expanding beyond infant formula into broader pediatric nutrition categories. The expanding regulatory perimeter is effectively enlarging the total addressable market, but it is doing so in a staggered, jurisdiction-specific manner that demands continuous regulatory intelligence rather than one-time due diligence.
Operationalizing the Report for 2026 Decision-Making
The value of this market study lies in its translation of macro trends into operational decisions. The report is structured to provide actionable intelligence across multiple business functions. It details the current and projected market size across the forecast period, giving finance and strategy teams a reliable basis for capacity planning, investment sizing, and revenue modeling. The segmentation analysis disaggregates demand by region, type, and application in a manner that allows product managers to identify where their offerings fit within the broader value chain and where white space or overexposure may exist.
Beyond quantitative baselines, the report captures the qualitative dynamics that numbers alone cannot convey. It maps the competitive profiles of core market participants, analyzing their headquarters, product architectures, patent positions, and recent developments to build a forward-looking view of competitive intent. Recent milestones, such as the European precision fermentation launch, Indian FSSAI approval, and Indonesia regulatory clearance, are contextualized to show how discrete events alter the supply-demand balance in specific territories.
The regulatory section aggregates the most consequential approval events and policy signals, providing a reference point for compliance teams and regulatory affairs managers. It distinguishes between approvals that expand the ingredient's use in mainstream food applications and those that are restricted to research-grade contexts, preventing costly misclassification of product intent. The raw material and production process context clarifies the technical dependencies that underpin supply reliability, enabling procurement leaders to assess vulnerabilities in the lactose supply chain and fermentation yield variability.
For M&A and business development teams, the concentration metrics and company profiles serve as a screening tool for potential partnerships, licensing opportunities, or acquisition targets. The report's architecture allows readers to filter information by relevance to their role, whether they are formulating a new product, negotiating a supply agreement, evaluating a market entry, or stress-testing a long-range financial model. The goal is to convert information into decision velocity, reducing the lag between signal detection and strategic action.
Strategic Horizons and Closing Perspective
As the 2'-FL market moves deeper into its growth curve, the differentiators that will separate winners from laggards are becoming increasingly clear. Regulatory fluency will remain paramount, as the ability to navigate and anticipate approval trajectories across jurisdictions will dictate which volumes can be commercialized and when. Production efficiency and strain intellectual property will determine who can compete on cost without sacrificing quality. Commercial execution, including formulation support, customer education, and supply chain resilience, will be the mechanism through which technical superiority is converted into market share.
The market data points to a future where 2'-FL is no longer a differentiating novelty but a standard expectation in premium early-life nutrition, with its footprint steadily expanding into adjacent wellness categories. Companies that treat this ingredient as a strategic platform rather than a commodity input will be best positioned to capture the value embedded in the forecast growth. The comprehensive intelligence contained in our Worldwide 2'-Fucosyllactose Market Report is designed to support that strategic posture, providing the depth, clarity, and forward-looking context needed to make informed decisions throughout the 2026 to 2032 period.
For detailed analysis of this topic, please visit the official page: Worldwide 2'-Fucosyllactose (2'-FL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com